What is an overdraft facility?
Some people want to build a house, others want to buy a new car. Some need a new washing machine, a new stove or a new dryer. Often everything is needed at once. Then Murphy's law strikes: anything that can go wrong, will go wrong. Money is needed in the short term. If it is available, that's fine. If not, an overdraft facility helps. It is colloquially also called a "dispokredit" or simply a "dispo".
If a bank grants an overdraft facility for a current account (Girokonto), the account holder can have access to more money than is actually in the account at that moment. It is thus a way to "overdraw" the account. The bank account slips into the "negative". For this loan the financial institution charges interest.
Banks introduced this form of credit in 1968. Since then it has enabled both businesses and private customers to bridge short-term financial tightness. This form of loan is the most used of all credit types. Millions of account holders use an overdraft facility every day. Why is that?
Above all because it is easy to get an overdraft approved. Usually any newly opened current account comes with the option to overdraw. The bank grants this possibility to the customer when the account is opened, provided that regular payments are credited to the account. The maximum amount of the credit line is usually based on the account holder’s income. This is set at the beginning. Afterwards any account holder can access this amount at any time. It is at the customer's disposal — hence the name overdraft.
It is not necessary to use the full credit amount every time. Partial amounts are also possible. Any amount within the agreed financial limit can be used. The money can also be repaid whenever it suits. An overdraft can therefore also be used for a longer period, although that is not advisable. Why is this discouraged? The overdraft interest that a bank charges for the overdraft facility are the most expensive interest rates in consumer lending.
This is because the bank may need to obtain money on the capital market at short notice. It does not know in advance when the overdraft will be used. Short-term borrowing costs are higher than those for long-term, predictable financing. The banks pass these costs on to customers via debit interest (Sollzinsen). They accrue for every day the account is in the negative and are therefore calculated on a day-by-day basis. A bank customer pays interest for an overdraft only for the period in which the overdraft facility is used — and not a day longer.
How does the overdraft facility work?
Nowadays almost every current account, including online current accounts, comes with this small loan when the account is opened. Banks often bundle services and the overdraft facility is part of such packages. If someone is of legal age, has a regular income and a positive Schufa rating, this credit option is usually set up quickly. After the first incoming payments to a current account, the overdraft limit is fixed.
Should the credit limit be changed later? Banks usually grant that informally, quickly and without complications. The overdraft limit can be increased retroactively, but of course it can also be reduced. So if you absolutely do not want to overdraw your account, you can inform the bank accordingly.
At most financial institutions, the setup of an overdraft facility is automatic on the bank's part. No active request is necessary. The account holder receives a "unilateral declaration of intent" from their bank in which the credit line is granted and the amount specified. This is usually sent by post. Sometimes this declaration also appears as additional information on the account statements. If no offer for an overdraft facility is provided, that is usually not a problem either. Then the customer must be proactive. Anyone who wants an overdraft facility for their current account contacts their bank directly and agrees on the conditions.
The amount of the overdraft limit is based on income — more precisely: on the net salary that is deposited in the account each month. Most banks offer a maximum credit line equal to two to three times this amount. Only after regular incoming payments have been credited to the account over a longer period will a bank consider the customer creditworthy. The bank trusts that the loan will be repaid within a certain period, even if that period is not fixed.
An advantage of the overdraft facility is that you only need to set it up once and not with every individual use, even after repaying the amount used. If you use the overdraft you do not have to apply for it again each time. It is always possible to simply withdraw more money than is actually in the account, of course only within the previously fixed limit. If you exceed this limit, you must expect very, very high debit interest. It is therefore advisable to stay within the overdraft limit. If that amount is not sufficient, other loan forms are cheaper. If the current account has been overdrawn, it should be balanced again as soon as possible. This typically happens with the next income payments. Additional cash deposits or transfers from a savings account to the current account can also eliminate the negative balance.
What determines the amount of the overdraft facility?
How much is allowed? In general everything is negotiable. How far should the account be allowed to be overdrawn? Banks use their own experience values. Which amount can someone with a regular income repay? When does it become tight and the account holder falls into excessive debt? Financial institutions can assess this. A common benchmark has emerged to determine the size of an overdraft facility. This guideline is two to three times the monthly income. Those who also own securities or a savings account have a chance of getting a higher overdraft. The credit line can also expand if, for example, a house can be used as collateral. The amount of the overdraft is always an individual agreement between bank and account holder.
Requirements for an overdraft facility
Who can get an overdraft facility?
As with other types of credit, being of legal age is the basic requirement to be granted an overdraft facility. Anyone aged 18 and over can use an overdraft — provided they hold a current account and regular payments are credited to it. These can be wages, salary, pension or maintenance payments, but also income from self-employment. The account holder should have no negative entries at Schufa. Negative Schufa entries and a poor Schufa score reduce the chances of obtaining an overdraft.
Those in vocational training or still studying will receive a loan from few banks easily. It becomes easier with a guarantor. Even easier is it with the overdraft facility. Nevertheless, regular deposits to the current account must be present. For students this can be BAföG or income from a student job; for trainees it is the training allowance. In both cases there must also be no negative Schufa score. No further collateral is usually required to receive the overdraft. However, many banks stipulate that they may seize assets if the short-term overdraft loan is not repaid. The bank then accesses the current account or any savings account that may exist. Securities owned can also be used as collateral.
Requirements for setting up an overdraft at a glance:
The borrower ...
- is at least 18 years old.
- has regular income.
- has no negative Schufa entries.
- is the holder of a current account.
Is an overdraft facility always granted on a current account?
Is there already an account into which salary payments go? Then a bank will usually send a "unilateral declaration of intent". Usually this is sent by post. Sometimes the letter is included as an additional account statement. With this letter a fixed overdraft limit is granted. The bank simply sets the limit at two to three times the monthly incoming income. This declaration of intent is legally an offer from the bank. If the overdraft is used for the first time, the offer is considered accepted.
If the bank does not send this declaration, the account holder must contact the bank to get an overdraft limit. The same applies if the overdraft is to be increased. Then the corresponding conditions are agreed. The bank considers whether money is regularly deposited into the account and takes the customer's current payment behavior into account. If the overdraft is not approved, the current account must be operated as a credit balance account. Overdrawing is then not possible.
Is an overdraft facility possible without a fixed income?
Finally 18 — now you can move out of your parents' home even without a fixed job. First check what you like and where you want to go. But the apartment should be furnished. A new sofa, a small kitchen and of course a modern TV. Wouldn't it be great to use the overdraft for that? Yes, it would. But unfortunately it is usually not possible. Without regular income or regular deposits to the current account, a bank will rarely grant an overdraft facility. Sometimes you can rely on the bank's goodwill and ask your bank whether this credit line can be granted even without regular income.
Unemployed or currently insolvent? Then the chances of getting an overdraft are also poor. Everything is a matter of agreement with the individual bank, but banks will not usually engage in uncertain situations. In fact, unemployment or insolvency signals a lack of creditworthiness. Banks assume such people cannot repay the loan. Unemployment benefits are not sufficient for lenders. It is unlikely that a loan will be approved on that basis. If someone becomes unemployed or has to file for insolvency, they must even expect that ongoing overdrafts may be terminated by the bank.
Interest on an overdraft facility
How high are the interest rates on an overdraft facility?
Even if you do not sign a separate contract with a bank: if you overdraw your account you must pay debit interest. The overdraft facility is the most expensive option when borrowing money. On average, savings banks, cooperative banks and Raiffeisen banks charge around 11% debit interest. The actual range is between 6 and 17 percent.
By comparison: on average a borrower pays 4–5% interest for the provision of funds on an installment loan. Depending on the institution, rates can start below 2%. The highest rate is up to a maximum of 12%. Online banks score particularly well here with very favorable conditions.
Is the granted overdraft not enough? If you exceed the credit line you will be charged heavily. The interest rates on such overdrafts are typically about 5% higher than the already expensive debit interest. Unlike installment loans, these are calculated to the day. That means interest is only charged for the days the account is in the red.
How is the interest for the overdraft facility calculated?
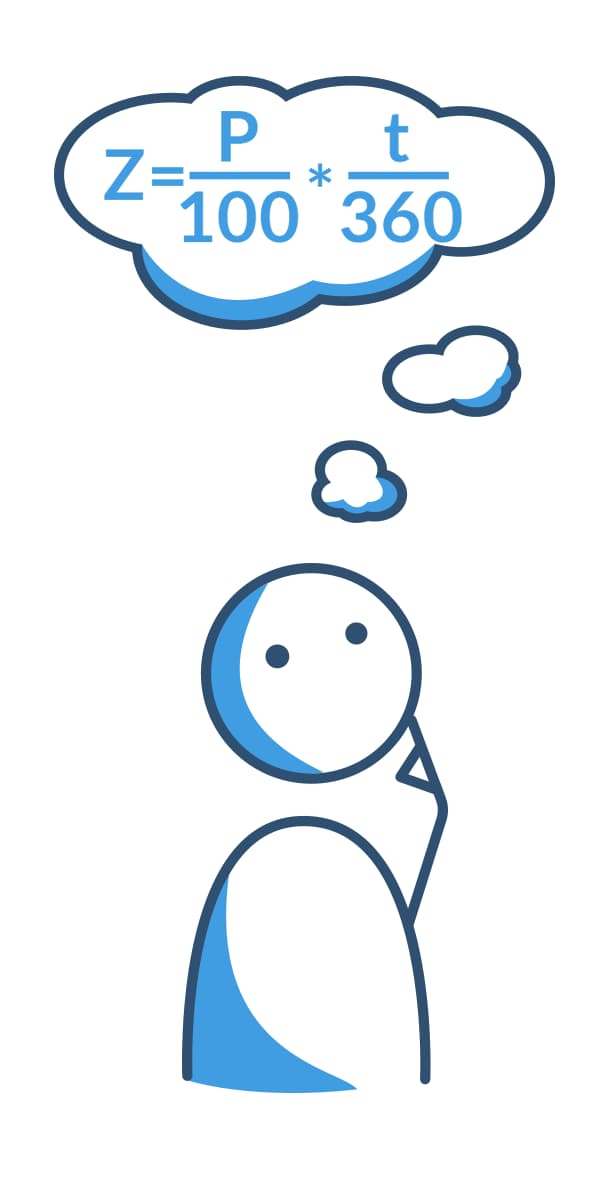
Banks use the following formula:
zu zahlender Zins = (loan amount * interest rate * number of days) : (365*100)
For example: the current account is overdrawn by 200 euros. It is 12 days in the red until the next income brings the account back into the black. The bank charges an interest rate of 12%. This results in the following amount.
zu zahlender Zins = (2001212) : (365*100) = 0.79 euros
Banks calculate interest daily because incoming payments can of course balance the account again. The negative amount decreases or increases if more money is withdrawn from the account. Banks therefore calculate the interest accruing daily, automatically summing it up at the end of the month for the month as a whole. They typically bill their customers the debit interest for the overdraft once a quarter.
Good to know: If a bank increases the interest rate on the current overdraft facility, the account holder can terminate it within six weeks. There is a special right of termination (Sonderkündigungsrecht). The higher interest will then not be charged. If the credit has been used and the account is overdrawn, the amount must be repaid upon termination.
Are overdraft interest rates the same at every bank?
Comparison pays off — also with overdrafts. You can save a lot of money. Who doesn't know it: at the beginning of the month many bills are debited very quickly? At the same time it often takes a little longer for incoming money to be posted to the current account. You can quickly slip into the red. It is good to pay the lowest debit interest during such unavoidable times. Are overdraft interest rates the same at all banks? No. There is a wide range of debit interest rates. Online lenders and direct banks usually offer cheaper rates than regional banks. How is this difference explained?
Savings banks, cooperative banks and other local banks have higher overhead costs. Direct banks and online banks usually employ fewer people than regional institutions. Local customers often have branches to visit for banking transactions and advice. The costs for running and maintaining these branches and paying staff are indirectly passed on to customers — including through higher interest rates. Internet banks like ING-Diba or Comdirect generally advise via chat, phone or email. The costs for physical branches are eliminated. Personnel costs are therefore lower. Internet banks thus have more leeway to pass on lower overdraft interest rates to customers.
Both — direct banks and regional banks — must obtain short-term funds on the capital market if a customer suddenly massively overdraws their current account. The bank never knows exactly when the overdraft will be used. Banks also pay interest for this short-term funding. These costs are higher than for planned banking operations. Financial institutions pass these costs on to customers through debit interest.
How can I find out the overdraft interest rate of a bank?
Everyone must know the debit interest rate they will face if they overdraw their account. Legislation has now mandated this. Since March 2016 banks are legally required to clearly disclose the level of their overdraft rates. These must be explained clearly and unambiguously on the banks' websites so that everyone can see what costs will arise when an overdraft facility is used. Sounds good. Nevertheless, some banks still obscure the concrete costs. Some institutions state a reference interest rate and show fees and surcharges without specifically naming the debit interest rate. Some determine the rate based on the customer's ability to pay and make it dependent on that.
Planning to switch banks? Or opening a new current account? Then compare thoroughly and don’t just look at the overdraft interest rate. Sometimes a bank has higher interest but charges high fees. What does issuance and use of the debit card or an additional credit card cost? Are there account maintenance fees? What are these costs? Can you withdraw cash at ATMs without extra charges? Or at a bank counter? Are there credit interest rates? All this should be taken into account when choosing a bank and a current account before switching. If you only want to switch banks because of high overdraft interest you should check whether it might be cheaper to use an installment loan or a revolving credit instead of an overdraft.
Termination of the overdraft facility
Can banks terminate the overdraft facility?
Banks regulate the termination of an overdraft or tolerated overdraft in their general terms and conditions (AGB). In most cases the overdraft limit can be reduced or entirely revoked at any time. If a customer declares insolvency, becomes unemployed or the customer's assets deteriorate significantly, banks can terminate the overdraft immediately — even without notice — if the reasons are serious. If enforcement proceedings threaten the borrower, termination is also possible. An ordinary termination takes the notice period into account. This is usually 30 days. If the termination is legally effective, any overdraft already used must be repaid immediately.
Is an overdraft subject to attachment?
An overdraft can be attached only if the account holder actually uses the overdraft. For example when a transfer or cash withdrawal takes place. It is therefore not the possible amount of the granted credit that can be attached, but only the money someone actually has at their disposal.
How long does an overdraft facility remain if no income is credited to the account?
If the customer's financial situation deteriorates, a bank can terminate the overdraft at any time. This also applies if no regular income is suddenly credited to the current account. How quickly termination occurs depends on the individual bank. If the customer has not been conspicuous so far and has always repaid loans regularly and on time, the bank may grant a larger leeway than to someone who constantly overdraws even the granted overdraft. Sometimes a bank does not contact the customer for several months even if no regular income is being received. Sometimes it asks after a few days or weeks. Banks are lenient if the missing income can be justified. Otherwise the overdraft will be terminated immediately. Usually you then have four weeks to balance the account. Afterwards the account must be operated on a credit basis, i.e. it can no longer be overdrawn.
Repayment of the overdraft facility
When must an overdraft be repaid? How is repayment carried out?
Are there fixed monthly instalments as with other loans? Is there a fixed due date for repayment? What is normal for other loan types is different for the overdraft. There are no strict repayment conditions. No repayment instalments are agreed with the bank. The account holder decides when to bring their account back into the black. When and which amounts are paid to clear the overdraft? Typically this happens automatically when the next salary or other deposits are credited. Consumer protection organisations warn against overstretching the overdraft for too long. You can quickly fall into a debt trap. It can be hard to get out of. An overdraft can be used year after year without a time limit. You should consider that long-term, permanent use is a very expensive form of borrowing. Even if base interest rates are particularly low in a given year, overdraft rates remain the highest interest in lending. It is advantageous to repay as quickly as possible because the interest burden then falls quickly and significantly. The actual interest paid thus also depends on your own behaviour. If you repay the overdraft quickly and in a disciplined manner, an overdraft is not expensive.
Can you exceed an overdraft facility?
While payments for other loan forms are fixed in time and amount, an overdraft can be repaid at will. It is therefore possible to use the limit over a longer period. However, overdraft interest is expensive. In this case a refinancing — i.e. using another loan form — should be considered.
Not only the period is flexible, the amount of repayments is also variable. Because of these wide-ranging options it is easy to reach the overdraft limit. What happens then? Initially nothing. It is quite possible to exceed the credit line and not only overdraw the current account but also overdraw the overdraft itself. Exceeding this limit should be avoided. The interest on exceeding the overdraft is significantly more expensive than the original debit interest. Often it is five percent or more. In this case it is better to speak to the bank. Even if the bank tolerates exceeding the credit limit, it can refuse or reverse debits and direct debits at any time if the account is not covered.
Talk to your bank advisor
If you reach the overdraft limit, speak to your bank advisor as soon as possible. This can avoid chargebacks and a lot of trouble. If it is clear that the overdraft is very short-term and sufficient funds will soon be available, a temporary overdraft loan can be agreed. Here the interest rate is again higher than for the regular overdraft. The overdraft is extended for a fixed period. It is better, however, to increase the overdraft in general. Whether this is approved depends on the bank and the customer's ability to pay.
Installment loan as an alternative
Another alternative is refinancing. The debt from the overdraft is converted into an installment loan. The debt is restructured. For this installment loan terms and fixed monthly payments are agreed. This has advantages for bank and borrower: the institution can be sure that the debt will be repaid and its risk decreases. The borrower reduces the debt continuously and benefits from a lower interest rate than the extremely high rate for overdrawing the overdraft.
Which banks grant overdraft facilities?
Whether internet bank, direct bank, private bank or branch bank — nowadays virtually all banks offer the possibility of setting up an overdraft facility for a current account. This applies to savings banks as well as cooperative banks. Millions of people use an overdraft at Dresdner Bank, Deutsche Bank or Commerzbank. In addition to the larger banks, smaller institutions among the roughly 2,000 banks in Germany also offer an overdraft facility for a current account. It is worth looking for comparisons on the internet. In this way you get a quick overview of the conditions a bank sets when granting an overdraft.
Direct banks and internet banks
Internet banks and direct banks often offer particularly favourable conditions for overdrafts. The advantage of online banks is obvious: they employ fewer staff and have lower premises costs because they forgo branches. They pass these savings on to their customers. Often the current account is free and the interest charged for using an overdraft is considerably lower than at other institutions. The requirements for granting an overdraft are the same as at branch banks. Creditworthiness must be assured. Direct banks also check the Schufa score and require a payslip or other proof of income. All this is necessary for the customer to be assessed as creditworthy.
Overdraft from foreign banks
Looking beyond the horizon can pay off. Whether in Switzerland, Liechtenstein or Austria — foreign banks also offer German customers the option of opening a current account. There is also the possibility of receiving an overdraft facility. In some cases this is possible without a Schufa inquiry. Within the Eurozone it is easy to use a current account with a foreign bank. The account is also managed in euros.
Is an overdraft possible without Schufa?
Who doesn't know this? An invoice and a reminder were overlooked and somehow the due amounts were not paid on time. You then get a negative Schufa entry. To be sure it gets its money back, a bank checks Schufa before granting credit. Is the prospective account holder or borrower creditworthy? Can they pay? Can they really repay bills and interest? In Germany an overdraft is usually not approved without Schufa information. But: it is still possible to get this flexible credit line with a negative Schufa score. Banks decide on a case-by-case basis. It matters how long the negative Schufa entry has existed. Will it soon be deleted? That is viewed positively. Are there savings or fixed-term deposit accounts? These are considered collateral for the overdraft. Can the applicant show regular salary payments? Is there even an unshakable employment contract? The account holder's current behaviour is also considered. Were invoices always paid on time? All of this influences the decision whether the overdraft is granted despite a negative Schufa entry. In the end it is always the individual bank's decision whether to grant the overdraft despite a negative Schufa score.
Advantages and disadvantages of the overdraft facility
Advantages of the overdraft facility
The overdraft facility is particularly flexible. This loan does not have to be repaid in fixed monthly instalments. It is repaid when it is possible. No fixed term is specified. The amount repaid can be freely chosen each time. Typically the next income will balance the account. It is also possible to transfer money from a savings account to the current account. The overdraft usually does not need to be approved each time — it is typically available immediately. Debit interest accrues only for the days the loan is actually used.
Advantages at a glance:
- Interest is charged only for the period used
- High flexibility
- Repayment possible at any time
- Repayments can be any amount
- No special collateral required
Disadvantages of the overdraft facility
Overdraft interest rates are expensive. That is probably the main disadvantage of this credit. That means it is only suitable for short-term financing. Constantly using the credit line over years is costly. If you overuse it, you must expect the bank to terminate the overdraft — immediately. In addition, the credit line is usually limited to two to three times the monthly net income; more is often difficult. If you exceed this credit line and overdraw the overdraft, you have to pay even higher credit interest.
Disadvantages at a glance:
- High interest rates
- Unsuitable for long-term use (bank can terminate at any time)
- Credit line is limited
Are there alternatives to the overdraft facility?
Because of the high interest rates, the overdraft should only be used when there is no other option and when it is clear that the negative balance can be cleared again very quickly. Constant or long-term overdrawing of the current account is not advisable. If short-term bottlenecks occur, check whether you can transfer money from other accounts. Is there a savings account or a daily money account? Is fixed-term deposit funds available on short notice? Before using the overdraft for larger amounts and longer terms, check whether the account can be topped up via these alternatives.
Revolving credit or standing credit (frame credit)
If you need a larger sum over a longer period, it is better to negotiate a revolving credit. It is also known as a call credit (Abrufkredit). It is cheaper than an overdraft but more expensive than a standard installment loan. With a revolving credit you can also borrow money at short notice.
As with an overdraft, an account is opened with a bank and the credit limit is set. For example, you negotiate that the limit encompasses €4,000. You can draw this amount as a lump sum or in several smaller amounts. Interest is charged only on the amount actually used. The interest on a revolving credit is tied to a reference rate, for example from the European Central Bank (ECB). If that rate falls, the loan interest falls; if it rises, loan interest and your personal interest burden rise. Consumers are flexible in designing repayment modalities with revolving credits as well. There are no fixed terms and no fixed monthly instalments. The customer decides when they repay which amount. Often the bank and borrower agree on a minimum monthly repayment amount, usually between one and two percent of the agreed credit limit.
A revolving credit must be applied for like an installment loan. The bank checks whether the applicant is liquid and reliable. Payslips are usually required. A current account is often specified as a reference account. The requested amount for the call credit is transferred to the current account.
If you know you will permanently overdraw your account, the revolving credit is a good alternative because interest rates are significantly lower. It is also advisable for loans needed for a short period, e.g. less than a year. For longer periods an installment loan is more appropriate.
Installment loan
An installment loan usually has even lower interest than a revolving credit. The term and the interest rate are fixed in advance. If you permanently or over a long period keep your current account in the red, it is worth converting that debt into an installment loan. The predetermined monthly payment reduces the debt steadily. The longer an installment loan runs, the more expensive it becomes. If you stretch the repayment over a long period, you can expect lower monthly payments, but very long terms increase total interest. Some banks charge interest surcharges for terms exceeding 60 months. The borrower must therefore expect regular monthly payments over several years. In return the loan will be fully repaid after a fixed period. At the same time balancing the current account again increases financial leeway for short-term needs. It is also possible to reduce an installment loan with one-off higher payments. However, you should ensure that partial repayments without prepayment penalties are agreed. Otherwise extra costs may arise for early repayment outside the agreed monthly instalments. It is advisable to compare the different terms of various banks before taking out a loan.
Avoiding over-indebtedness
The cheapest alternative is to avoid a large account overdraft from the start. Debts often form when you lose sight of your finances. It is helpful to get an overview: list all income and expenses. This quickly shows how liquid you are and whether you have financial room for manoeuvre. Shortages will occur occasionally. When you recognise them, consider where you can save or whether you can increase income. Building reserves on a daily money account, for example, is also a safer option. These help if you unexpectedly face a tight financial situation. Sometimes this happens faster than you think: several appliances may fail at once or unexpected medical costs arise because some expenses are not covered by health insurance. If you have built up reserves, you do not have to overdraw the overdraft.
Overdraft facility and current account credit - What is the difference?
Some people speak of a current account credit (Kontokorrentkredit), others of an overdraft facility. What is what? How do they differ? These forms of credit are very similar. In both cases a certain financial scope is set up for an account. The account holder can overdraw it up to a predetermined amount — in other words borrow money from the bank. Each bank charges interest for that. The amounts borrowed by the customer are variable each time. You can use the whole credit sum at once or smaller parts. These are repaid as the account holder wishes. Up to the agreed credit limit, new amounts can always be borrowed again.
Up to this point overdraft facility and current account credit are the same. The difference lies in the use of the loan. A dispo is granted to private customers and is therefore a form of consumer credit. An overdraft facility is usually set up on a current account used for salary payments.
Current account credits are made available for business accounts. Companies, self-employed people and enterprises can thus pay invoices, wages and salaries or other financial obligations before payments from customers are credited to the account. Banks scrutinise companies intensively for creditworthiness before granting current account credits. This is not the case with an overdraft facility.