Maximum interest rate - What is it?
The maximum interest rate defines the highest rate for the contractually pre-agreed interest rate that both contracting parties in the finance and lending sector can or must reckon with. In this respect, the maximum interest rate in lending and finance is broadly similar to the so-called maximum interest rate in the insurance sector. The maximum interest rate can also be referred to as an interest cap. Agreeing such a cap for an interest rate makes sense when it concerns a loan with a variable interest rate. While an interest cap protects the borrower, an interest floor is used to protect banks.
Depending on the set level of the maximum possible interest rate, the maximum interest rate can therefore be both a benefit and a burden for either contracting party. It primarily depends on who holds a credit balance — for example in the form of a loan — or who invests funds, such as in savings deposits.
However, legislators have left the permissible maximum interest rate for credit transactions largely unrestricted and therefore more flexible. This is because the maximum interest rate is primarily determined by demand and the current state of the market economy. The higher the demand for loans, the higher the interest rates that often have to be paid for a loan or credit.
Base rate and actuarial maximum interest rate
Above all, the base rate — and thus also the maximum interest rate — is influenced by the European Central Bank (ECB). When the base rate is low, low interest is paid on savings deposits, and low interest is also charged on loans. From 2008, interest rates fell both on savings deposits and on mortgage rates. Since 2016, however, a slight upward trend has been visible again.
The base rate should not be confused with the basis interest rate (Basiszinssatz), which is also calculated and published in connection with central bank and legal mechanisms. The basis interest rate is used to assess capital services.
For the actuarial maximum interest rate (Höchstrechnungszinssatz), the average returns (yields) on government bonds are the basis for the calculation. An initial proposal for this rate is submitted, among others, by the Bundesanstalt für Finanzdienstleistungsaufsicht and is finally determined by the Bundesministerium für Finanzen. The value is set in percent and refers to the average yield of government bonds with a 10‑year term. This rate is relevant for the so‑called coverage reserves (Deckungsrückstellung) of life insurance policies and similar contracts. The coverage reserve is an accounting term that describes the value the insurer owes to the insured (simplified). The Regulation on actuarial principles for coverage reserves (Deckungsrückstellungsverordnung - DeckRV) regulates the maximum interest rate for insurance contracts in § 2.
The actuarial maximum interest rate or technical interest rate and the guaranteed interest rate are often mentioned in connection with the maximum interest rate, but they mean something different.
Where the maximum interest rate occurs
In addition to the current market situation, the precise definition of the maximum interest rate also depends heavily on the overall lending context. Just as lenders, types of credit and borrowers differ, individual loan offers are often variable. This is reflected in the loan interest rate and its maximum interest rate. There are contracts in which the interest always decreases with the level of the falling outstanding balance, and there are loans in which the interest rate is tiered or fixed for an agreed period.
The latter two procedures occur more often in lending than, for example, in savings deposits. In the case of savings deposits, such arrangements could be disadvantageous for the saver. Therefore, rising and variable interest rates are preferred for savings deposits, which, for example, increase annually by a pre-agreed interest amount.
In a savings contract, the maximum interest rate then denotes the highest interest rate that an investor is credited on their saved balance. Long‑term savings contracts can, however, often be adjusted after some years of term, just like loans and credits that are repaid over a longer period. A good example is mortgages in the real estate sector.
The advantages of a maximum interest rate in the credit sector generally outweigh the disadvantages for the borrower. Because with the maximum interest rate specified in the loan agreement, the borrower always knows the highest rate of interest they can expect to pay.
Interest rate, nominal rate and real rate
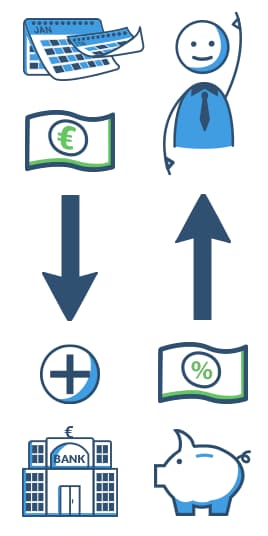
But what exactly is interest and how is the interest rate and the maximum interest rate calculated from it? The term interest derives from the Latin word census, which roughly translates as "estimate of wealth." In finance and lending, interest is understood as the compensation that the borrower (debtor) pays to the lender (creditor) for the capital lent to them.
It is similar with savings deposits, where the investor and saver naturally receives interest on their invested capital on a monthly basis. The interest rate, however, determines the amount of the compensation, which is paid at regular intervals and, in lending, is always paid together with the repayment instalment. The loan interest rate thus determines, based on its level and the outstanding balance, the amount of the monthly borrowing costs.
However, the interest rate is variable in many loan forms, as it also depends on the outstanding balance. Sometimes this happens annually, sometimes monthly — and in other credit types the interest rate is fixed for a contractually agreed period. The borrower can sometimes benefit from this if overall interest rates rise due to the volatile financial market situation.
The disadvantage, however, is that the interest rate does not adjust when general market rates fall. But interest is not all the same. For example, in lending one often speaks not only of interest and interest rate and maximum interest rate, but also of the debit interest (Sollzins), credit interest (Habenzins), nominal interest rate (Nominalzins), real interest rate (Realzins) and effective interest rate (Effektivzins).
The debit interest (Sollzins) is the interest that the debtor must pay to the creditor over the period of borrowing and repayment for the provision of the money. Credit interest (Habenzins) is spoken of when the creditor receives interest from a debtor or when a saver receives interest from their bank. Here a more detailed distinction is made:
The nominal interest rate (Nominalzins) always refers to the agreed or paid interest rate of a loan. The real interest rate (Realzins) is the rate that remains after the inflation rate has been subtracted from the nominal rate. As a result, the real interest rate can be negative if the inflation rate is higher than the nominal interest rate. The effective interest rate (Effektivzins) is the rate that results from the nominal rate and any other factors of price and cost determination.
Since the percentage rate of interest always determines the actual level of interest by which the monthly or annual interest payment or payout is made, the maximum interest rate slots in here. It relates to the nominal rate while at the same time determining its maximum permissible level.
Why is there a maximum interest rate?
The maximum interest rate was introduced by the German legislator and at the international level in 1983 to protect both contracting parties from excessively rising interest developments. However, this legislative change does not include the lending sector.
In the German Civil Code (BGB) the legislator did not set a maximum interest level, but allows financial and monetary institutions very free and flexible structuring of interest rates so that they can optimally adapt the interest charged to the market economy, demand and other factors such as increased risk. The maximum interest rate known from lending is more or less an additional protection that the lender voluntarily grants to the borrower.
But as already indicated, this does not always and in every context have exclusively advantageous effects. Therefore, it is extremely important to compare several loan offers before deciding on one. Above all because the type of loan and the lender can differ significantly from each other in terms of the maximum rate.
Not infrequently, an extensive search or consultation at the lending institution will reveal a loan that fits your own expectations, life situation and financial situation down to the smallest detail.