Loans with a fixed rate
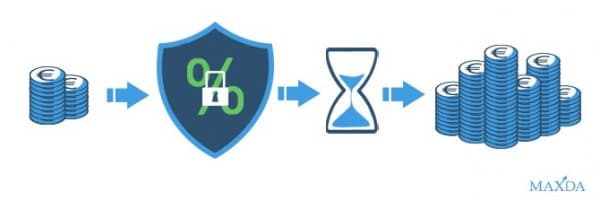
When a lender, for example a bank, grants a loan, the interest or interest rate represents its earnings and its security. Therefore, installment loans with a fixed interest rate (also fixed-rate loan) are interesting for both parties. Such an interest-rate fixation always takes place for a certain period, which is usually shorter than the total term of the loan. This fixed interest rate is often also called a fixed-rate locking. This allows both parties (borrower and lender) to calculate their income or expenses, at least in the near future. After the fixed-rate period expires, a new fixed rate is set, or a fixed rate may be waived. In the latter case, it is usually possible to make a larger repayment. Or even repay the entire remaining balance. However, a fixed rate is an attractive option for both parties. The fixed rate allows the bank to calculate its exact earnings from the fixed-rate loan, and it offers the borrower a bit more security. Fixed-rate loans protect the borrower if interest rates rise, because usually the outstanding balance is still so high that full repayment is not yet possible. As long as the lender cannot detect any changes in creditworthiness, there is no reason for them to change the fixed rate or even to demand full immediate repayment.
Loans with lower burden thanks to fixed-rate period
During the term of a loan there are many uncertainties in the borrower's life. However, one thing the borrower can be sure of is protection against rising interest rates during the fixed-rate period. Such a fixed-rate period is particularly interesting for long-term loans, especially in times of rising interest rates, and accordingly fixed-rate loans protect the borrower from having to pay more—temporarily—over a long period.
Setting the fixed rate
There are two ways to calculate the interest for installment loans with a fixed rate. Firstly, the creditworthiness-based option, where the fixed rate depends on the individual borrower's creditworthiness. The second variant is the creditworthiness-independent rate determination. Here only external factors are considered. This means a loan is offered that provides the same conditions for everyone. Preconditions for a lower fixed rate are the amount of the loan and the term. Creditworthiness-independent loans still require a Schufa check. The borrower's financial circumstances must meet the standards of creditworthiness; otherwise, even with the creditworthiness-independent variant, the loan application may be rejected. So creditworthiness also plays a role in creditworthiness-independent fixed-rate loans. Only in the creditworthiness-based variant is the fixed rate tailored to the individual borrower. It is still important that the borrower obtains detailed information beforehand and carries out a loan comparison. The comparison can help save high costs. Priority should be given to comparing the different interest rates, but costs such as fees should also be included in the comparison.
Not exclusively for business customers
Fixed-rate loans can be used by both business customers and consumers. The main difference is that interest-rate fixations for business customers can be possible from just one month, i.e., also for short terms. If a consumer is interested in fixed-rate loans, the loan term mainly determines the level of the fixed rate. Business customers may also have the option, after the term expires, to repay the loan partially or even in full. For fixed-rate loans for private customers, a follow-up financing negotiation is usually required; a partial repayment may possibly also be part of the negotiation. Full repayment is only limitedly an option for a consumer and is rarely offered. For private customers, the interest rate is adjusted after the fixed-rate period, meaning that any interest rate change is taken into account and the current rate is used. For business customers, however, the remaining interest and a margin agreed at contract signing are often used if the remaining balance is not fully repaid.
Consumers can also cancel for long terms
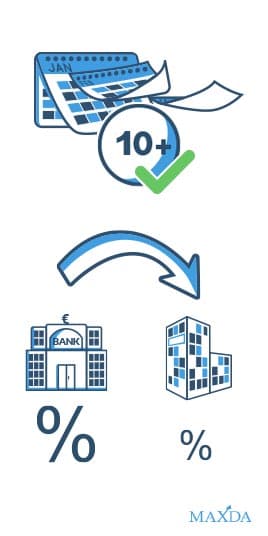
Fixed-rate loans mean that the private borrower is initially protected from a higher interest rate, but this also binds them to the lender or bank for the duration of the fixed-rate period. However, fixed-rate loans also offer the option to cancel, and this applies to private customers as well. This is a good option for long-term loans and can only be used if the loan term is more than ten years. If this is the case, and the loan has been running, for example, for eleven years, the borrower can cancel the lender's contract and carry out a refinancing. However, the borrower must still observe the six-month notice period. So if, for example, nine years remain and the borrower receives a better offer, they are free to switch to the better offer before the end of the intended term.
Fixed-rate loans - Flexible despite the commitment
Fixed-rate loans therefore offer many advantages for the borrower despite the commitment. With long terms, the borrower is bound to the respective provider or bank with the specified interest rates, but the fixed rate provides a certain calculatory certainty. One is also protected from the interest rate change risk during the binding period. Even this, however, can be freely negotiated in creditworthiness-based loans. The lender simply has to agree. The borrower is even flexible enough to refinance after ten years; fixed-rate loans are therefore an individual and flexible way to realize bigger dreams despite being bound to the lender.
Fixed-rate savings
Fixed interest rates also exist for fixed-rate savings. Fixed-rate savings are also called fixed-rate bonds and are implemented in a so-called fixed-term deposit account. A fixed deposit is placed for a certain period and the interest rate remains the same during that time. The savings are protected by the banks' deposit insurance and are therefore not affected by market fluctuations. Deposit insurance applies to the fixed-term deposit account, the instant-access savings account and the checking account. In an instant-access savings account, on the other hand, savings can be deposited at the current daily savings rate and accumulated. An investment can thus be made either in a fixed-term deposit account or an instant-access savings account. The difference between investing as a fixed-term deposit or as instant-access savings is that the money in an instant-access savings account is not restricted to a certain term compared to a fixed-term deposit account. With a fixed-term deposit account, access to the saved money is possible at the end of the term.