Loan approval by banks
Most banks earn their money from lending: after all, they receive capital or loan amounts on better terms than consumers. Nevertheless, every credit institution also faces a certain risk when lending capital. If the debtor is no longer able to meet the payment obligations, i.e. the monthly installments, the bank may suffer a loss on its claims. For people who have low creditworthiness, this is referred to as a loan in difficult cases. Whether an application for a loan in difficult cases is best submitted to the house bank or to another bank with different loan offers should be researched thoroughly in advance. The house bank may be the closest option, but it can offer the applicant worse terms regarding durations and installments or may involve upfront costs. In particular, upfront costs can often be avoided at many banks. Therefore it is worth comparing different loan offers before applying for a loan.
Income determines garnishment
The reasons can be very different. In general, the reason is that the income is not high enough to make repayment of the loan possible. For banks, what matters regarding the amount is whether the salary can, if necessary, also be garnished. There are corresponding values for garnishment limits that must be exceeded in order for the bank to be able to enforce its claims. For a single person, a net income of currently about 1,030 euros per month must first be exceeded before the possibility of wage garnishment exists. If the debtor also has children for whom they are liable to pay maintenance, the limits shift further upwards. Concretely, this means that it quickly becomes almost impossible for banks to assert their claims. It must be taken into account, however, that income means all earnings. In addition to employment income, this can also include, for example, capital gains.
Negative entry: Loan without Schufa can help
\
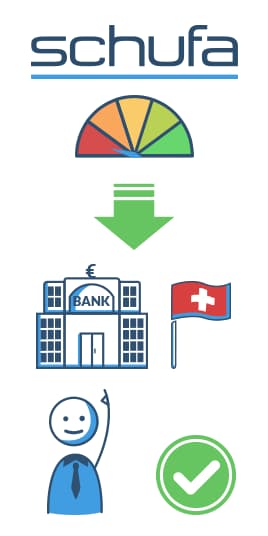
In addition to income, German banks also require a Schufa report. The organization records how reliable the debtor has been in repaying loans in the past. Therefore, a Schufa check is indispensable for many credit institutions. In addition to loans, payment obligations such as mobile phone contracts or installment payments are also taken into account. If a negative entry is noted in the file because a repayment was not made on time, the prospects for another loan are poor. An exception is Swiss banks, which grant the so-called Swiss loan. For this loan the term is set at around 42 months and the loan amount at 3,500 euros. Differences occur only in the interest conditions permitted by the bank. In principle, a Swiss loan is comparatively somewhat more expensive. In return, a Schufa check is waived, which is due to the fact that Schufa is not responsible for Swiss banks. This not only enables particularly quick disbursement of the loan amount, but also makes a loan in difficult cases possible with Maxda. However, there are no compromises regarding income: the already mentioned option of wage garnishment is the only means Swiss banks have to have their claims satisfied. Loans are therefore often refused if the income consists of unemployment benefits or BAföG, unless a creditworthy guarantor is named. Age can also cause a loan to be either refused or the debtor to have to pay high risk surcharges. At many banks, loans are not always easily granted to customers who are older than 58 years. In Germany, Swiss loans are usually offered through experienced loan brokers like Maxda.
Compensating risk with loan collateral
If some criteria are not met, this does not necessarily mean that the application and thus the financing will be rejected. In such cases, a collateral provided by the applicant can help further, provided it is accepted by the bank. These can be capital investments such as life insurance policies; but of course also real estate or vehicles. Since a car generally depreciates in value, the vehicle must not be too old. Most banks accept about five years as the maximum. In addition, the vehicle registration document part I must then be handed over to the bank so that the vehicle cannot be sold by the debtor during the loan term. There must also be insurance cover that compensates the damage even in the event of a total loss and independent of one's own fault. For real estate, each case is examined individually. In some regions with a difficult real estate market, it is quite possible that the bank will refuse this type of security.
A guarantee can secure a loan
If collateral is completely lacking, a guarantee can also secure the conclusion of a loan even in difficult cases and be the appropriate solution. The prerequisite for this is a friend or family member who has sufficient creditworthiness - and who trusts the debtor. Because with a guarantee the guarantor is called upon to pay the remaining debt if the debtor no longer meets the payment obligations. Apart from these risks, such a guarantee allows the conclusion of cheaper loans, because the lender can demand repayment from two debtors and the risk of a complete default is therefore significantly reduced.
Private loans in difficult cases
If the possibility of a guarantor is not available either, a private loan broker can help with a loan request. In principle, a private loan in difficult cases has crucial advantages: if the money is not lent commercially, i.e. for the purpose of making a profit, lenders do not have to adhere to certain requirements — and that also includes checking creditworthiness. Thus, in theory a private loan is possible even when absolutely no creditworthiness exists. Loans are traded online on corresponding platforms. If a private loan is to be used, a profile must first be created. The loan broker then checks the accuracy of the information, for example if there are any collateral that improve the prospects of a loan. Once the profile is activated, the loan seeker can place an ad for a loan request. They have the opportunity to describe the reasons for the loan in detail and create understanding for their own situation. This opportunity should definitely be used, because unlike a bank the subjective assessment by a private lender is often of decisive importance. However, the borrower must be prepared for a private loan to be significantly more expensive than a comparable bank loan. Because the risk of default is comparatively high, the loan is secured with risk surcharges. Nevertheless, both sides can sometimes benefit from such loan mediation: the borrower receives a loan even in a complicated situation; and the lender gets their money at a higher interest rate than on the free capital market.
Conclusion: Even in seemingly hopeless situations there are options
Ultimately, the conclusion remains that even in difficult cases there are a number of options to have a loan application approved. If the income is too low to obtain the desired loan amount, collateral is the obvious solution. They ensure that the bank can even grant financing on very good terms. If collateral is not available, the possibility of obtaining a loan through a guarantee should first be examined. A guarantee, however, requires a guarantor with good creditworthiness and trust in the debtor. If the Schufa check shows negative entries, a Swiss loan can also be used. Another way out are private loans. The advantage that the required creditworthiness is low is at the same time the biggest disadvantage: due to the high risk of default, interest rates are correspondingly high and make a loan from a broker an expensive alternative.