What is a fee?
"May God reward you." Anyone who has been to Bavaria has surely heard this phrase. "May God reward you" is used as a way of saying thank you. May God repay it, show gratitude, or be appreciative. It is usually said when someone has given something away or helped. It is the compensation for an often good deed. Here, "vergolden" (to repay) and "entgelten" have the same meaning.
A fee therefore primarily denotes a counter-performance — in any form. If a service is not free, it is compensated. Consulting, advice, coaching, window cleaning, mowing the lawn, taking a taxi — someone does something for someone else. For that they are paid. Or remunerated. They receive a fee. All three descriptions mean the same. That is why the term fee is often used synonymously with wage, salary
You pay a fee for the service received. In most cases this is money. But other arrangements can also be made. In the Middle Ages and even later, services on large estates, for example, were compensated in kind, i.e. paid for. The farmhand received, for cleaning the stables, caring for the animals and similar tasks, as payment for example potatoes, beets, wheat. Often the agricultural workers were also allowed to live on the estate. So payment without money occurred. A rendered service receives a countervalue. That is what the fee denotes.
Are there also unpaid counter-performances?
Hans mows his neighbor Peter’s lawn. He does this regularly, once a week. In return, Peter goes shopping for Hans. One service is compensated by a counter-performance. In this sense a fee can be a barter transaction. If Peter lends Hans his lawn mower because Hans mows the lawn, that is a loan, not a fee. Lending something is the gratuitous transfer of an item. Otherwise the lawn mower would be rented. The rent to be paid, in turn, is a fee.
In lending (credit) law, a guarantee (Bürgschaft) belongs to the gratuitous legal transactions. A guarantee is a way of guaranteeing repayment of a loan. It plays an important role in granting loans. A guarantor undertakes to pay if the original borrower defaults and can no longer pay. In a guarantee contract a service is thus covered by a counter-performance, without a fee being established.
Where can fee agreements be found?
First of all, a contract is concluded between two parties. It states that a counter-performance will be provided for a service. Whoever lives in a rented apartment pays a monthly amount. This is recorded in the rental agreement. It is the fee for the service that the apartment is provided. In this case the service (apartment) conditions the corresponding counter-performance (rent).
The same applies in an employment contract. Whoever starts a new job receives wages or a salary as an employee. It is the fee for the work performed, i.e. remuneration for work. Interns often work without pay. They receive no salary for the time they are in the company, working and learning. They are not remunerated. Essentially they give the company their labor as a gift, since they receive no remuneration.
Do you want to fulfill the dream of owning a home? Usually more money is needed than you happen to have in your savings account. A loan is taken out. Because the bank lends someone money for a certain period, it wants to be paid. It therefore charges interest. That too is a fee. Its amount is agreed in the loan or credit agreement. Repayment of the borrowed sum is not a fee. Only the activity — i.e. making the requested amount available — is remunerated to the credit institution. Once the loan is fully repaid, the remuneration ends and interest no longer has to be paid.
Fees also occur in the credit and financial sector.
Fees in the credit sector
Banks charge charges. Whoever wants to have an account usually has to pay fees for it. Fees are charged for providing an account and for account management, which must be paid to the bank. Often these charges are mistakenly referred to as fees. However, they are not a fee. Charges are paid for an official activity. In this case for the provision of the account.
In the credit sector the distinction between charges and fees becomes blurred. Whoever wants to take out a loan will be charged loan or lending fees. The credit institution provides a service and demands a counter-performance for it. In this case charges are equated with fees.
When are fees permissible?
Are credit institutions allowed to demand fees and charges however they please? Can they independently determine the amount, duration and reason for the fee? The legislator has the consumer’s welfare in mind. Therefore it checks who charges what interest, fees and costs for what. How are interest rates calculated? Banks may remunerate themselves for special services and for managing an account. It is therefore permissible to charge customers a fee for this. For services that the lender must provide by law — i.e. that it is legally obliged to provide — the costs may not be passed on to the customer as a fee.
Fees that, according to the Federal Court of Justice (BGH), may be charged
Prepayment compensation as a fee
Isn't it nice when a loan can be repaid before the agreed term has expired? For the customer, yes. For the bank, not so much. Credit institutions count on the money a customer pays for the provision of the sum. It is their "earning." If a loan is repaid early, the bank does not receive the interest it originally expected. It loses that profit. For that the credit institution may demand a fee — the so-called prepayment compensation. As compensation for the lost profit. However, the fee must not be calculated as a flat rate.
Commitment interest as a fee
From the point in time when a loan is made available, interest is payable to the bank. This also applies if the credit cannot yet be used. When is that the case? That is the case when, for example, the house construction is delayed. Bad weather prevents the masons from working? An early frost suddenly makes working on the future home impossible? If money has already been requested, is available but not yet needed, one must also pay a fee for it — the commitment interest.
Fee for non-acceptance
Everything was completed successfully: the loan was applied for, examined and approved by the bank. Repayment installments and interest for the loan term were calculated. But suddenly the customer no longer wants the money. The loan is not taken up. Inherited? Received a better offer? Discovered an alternative source of financing? Whatever the reason for not accepting the already provided loan, it costs. The bank has been deprived of its interest income. The credit institution can charge a compensation for non-acceptance.
When is a payment not a fee?
If someone does not pay their installments on time, they fall into default. Default interest can be charged for this. Contracts also usually regulate which measures apply if the contract is breached or abused. These are the so-called contractual penalties. If someone has suffered a loss because contractual conditions were not complied with by one party, the other contracting party can claim damages. All of these points exceed the counter-performance and are not calculable in advance. They are not to be seen as fees. They are rather a punishment when the contract is violated.
Where does the term "Entgelt" come from?
The term "Entgelt" goes back to "gelten", which was already used in the Middle Ages. In Old High German the word was "geltan", which can be equated with "to be valid" and "to be worth something." "Entgelt" then formed over time from the word "gelten". It stands for "to be worth something" and, together with "vergelten", evolved over the years. In the economic sphere, "vergelten" still means to repay something today.
If you make clear from which word the term comes, the only correct spelling quickly becomes clear and unmistakable. "Entgelt" is the noun of the verb entgelten. It is something you are paid for. Or, put another way: you get something recompensed.
"Entgelten" is therefore another expression for remunerate, compensate, reimburse, or make good. Repaying or replacing can also be mentioned as synonyms. These are words commonly used in the financial sector, but also in commercial, economic and legal language.
A fee is therefore what you receive, for example, as remuneration for your work (remuneration for work). Although it is often associated with an amount of money, it is not an "Entgeld". Because a fee can also be possible in other forms. Services can be compensated by other services. Here barter replaces monetary compensation. Although this is often paid at the end of a month or after completion of a service, this payment has nothing to do with "end". "Endgeld" would therefore be doubly wrong. This spelling mistake shows the confusion with "Geld" (money). And the prefix "Ent-" stands for "back" or "away". It is therefore about repaying something. It has nothing to do with the end of a period.
How do you spell Entgelt? Endgeld or Entgeld or Entgelt?
The only correct spelling is Entgelt. All other variants are simply wrong.
Yes, this word really is written with a "t" at both the beginning and the end.
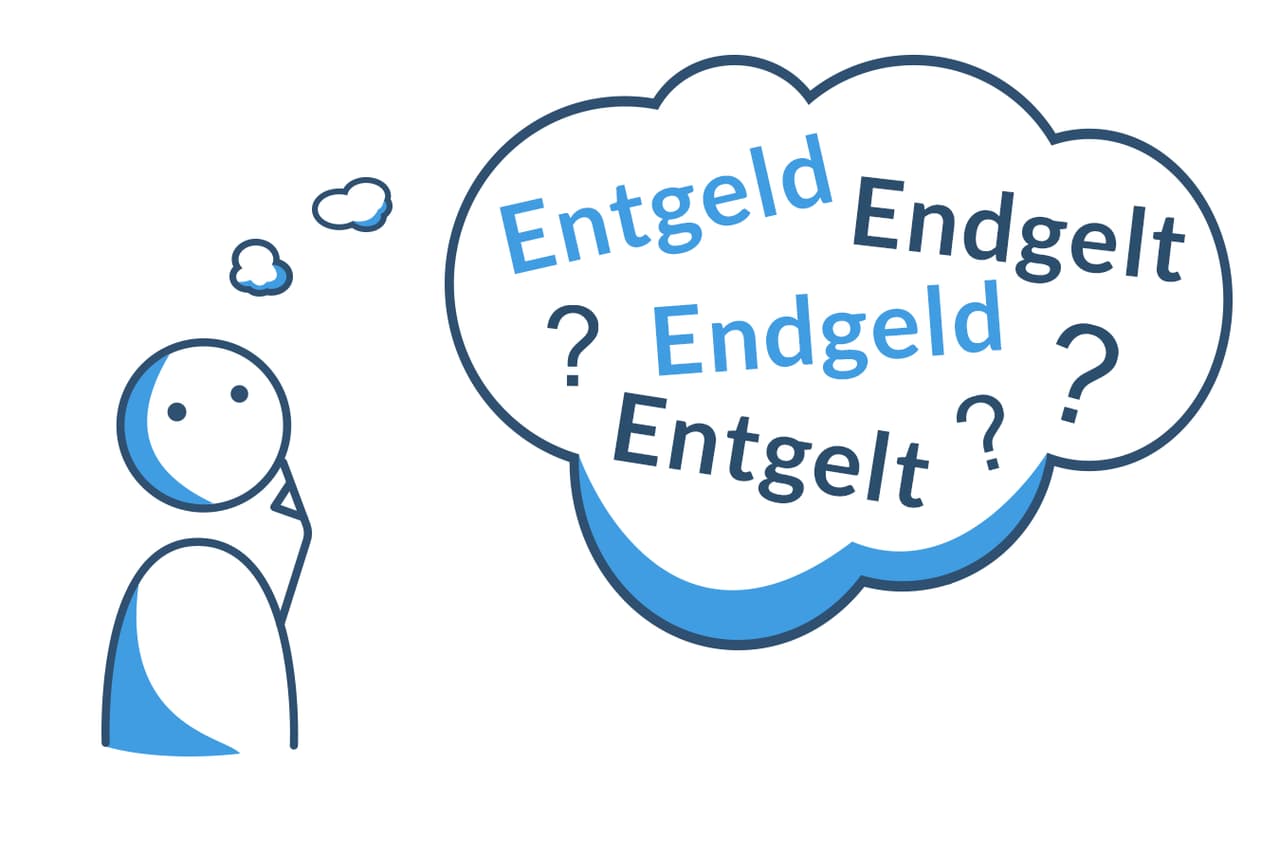
Everything has an end. At the end you receive your money. So it's an "end-money" ("Endgeld"). There are several variants in which the term "Entgelt" is written. Common incorrect spellings are "Entgeld", "Endgeld" or "Endgelt". These spellings are widespread. This phenomenon can be logically explained. The word Entgelt is mainly used in the financial sector. For example, you receive a fee for your work. Banks calculate a fee for providing the loan. So it has something to do with money. That may be conceptually correct, but orthographically it is still wrong.