A creditor is a person who is in an obligation (debt relationship) toward another person and can demand a performance or omission. The creditor therefore faces the debtor.
The creditor is also called a creditor (Kreditor).
The term is derived from the Italian word "credere", which means "to believe". Accordingly, the person providing the debt believes that the debtor is able and will perform the owed obligation.
The term "creditor" is used in connection with the law of obligations (Schuldrecht) (§ 241 Abs. 1 Satz 1 BGB). The law of obligations is part of private law, which regulates the relationships between natural and legal persons. If there is a legal relationship between the creditor and the debtor, this is called an obligation (Schuldverhältnis).
The debtor is also called a debtor (Debitor). Debitor comes from the Latin word “debere”, which means “to owe”. It is thus the complementary term to Kreditor.
Different types of obligations
Obligations are distinguished into:
- contractual obligations,
- quasi-contractual obligations,
- statutory obligations.
In many obligations, parties are both debtor and creditor at the same time. This is, for example, the case in a purchase contract.
Here a mutually binding obligation exists between buyer and seller. In principle, several creditors can be involved in an obligation. These are referred to as multiple creditors.
Forms of multiple creditors
There are the following forms of multiple creditors:
- Partial creditorship (§ 420 BGB)
- Joint creditorship (§ 428 BGB)
- Community of creditors (§ 432 BGB)
In partial creditorship, all participating creditors independently have the possibility to demand a part of the performance. If there are no contractual arrangements, then, in doubt, all participating creditors receive an equally sized share of the performance.
However, a prerequisite is that the owed performance is divisible. That means the performance must not be diminished in value by the division. If it is a monetary claim, it can be divided without difficulty. If a living animal is owed, it cannot be divided. It is different for a herd of animals: if an entire herd is owed, it can be split into smaller herds. In practice, however, partial creditorship is rather the exception.
Joint creditorship
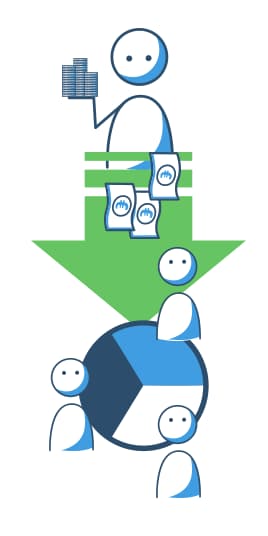
While in partial creditorship all creditors may claim only a part of the performance, creditors in joint creditorship are entitled to claim the entire performance for themselves. The claim is not divided. However, the debtor only has to perform once and can choose to whom he makes the performance. This extinguishes the claim against the other creditors of the joint creditorship.
To ensure that each creditor nevertheless receives something, the recipient of the performance is obliged to compensate his co-creditors. The proportions are agreed upon internally. If there are no agreements, joint creditors are obliged to equal shares. The last possible form of multiple creditors is the community of creditors. This differs from the other forms in that the debtor can only perform to all community creditors jointly.
If the debtor satisfies only one creditor, the claim does not extinguish. Nevertheless, the debtor performs only once and the internal relationship is not relevant for the debtor. There are three types of claims in creditor communities: joint ownership communities (Gesamthandsgemeinschaften), fractional communities (Bruchteilsgemeinschaften), and, finally, performances that are indivisible in the natural sense.
Creditor and debtor
If a credit institution, a private lender or a bank provides a loan, the lender is referred to as the creditor, while the borrower becomes the debtor. The debtor undertakes to repay or amortize the loan within an agreed and specified framework. The creditor has a right under the law of obligations against the debtor, which allows him to demand interest in addition to the borrowed sum.
If the debtor falls into default, the creditor asserts his claims by means of extrajudicial reminders. For this purpose, the creditor sends the debtor a letter requesting payment.
To avoid default interest and further high costs, debtors should contact the creditors no later than upon receipt of the payment request to arrange a deferral of the remaining sum or an instalment plan. Those debtors who do not respond to the reminder must expect dunning proceedings. These dunning proceedings are initiated by the competent local court.
Objection
After service, debtors have two weeks to file an objection. However, an objection only makes sense if the claimed payment is partially or entirely unfounded. If the debtor does not file an objection and makes no further payment, the creditor will apply to the local court for an enforcement order (Vollstreckungsbescheid), which allows him to enforce the asserted claims by a bailiff or by wage and salary garnishment. Without a timely objection, the enforcement order becomes final. Such titled claims become time-barred after 30 years and establish that the creditor has a legal claim.
If enforcement proceedings occur, the most common measures are seizure of assets, a sworn affidavit with disclosure of assets, and garnishment of claims (wages, salary, bank balances, social benefits). Creditors frequently make use of debt collection agencies to collect claims. Such collection agencies are usually private companies whose task is to collect the creditor’s claims in various ways.
Without a thorough examination of the asserted claims, debtors should not sign pre-formulated agreements or even admissions of debt from a collection service.
What risk does the creditor bear?
When an obligation arises, the creditor is the one taking a risk. He does not know whether and in what form the debtor will be able to make regular repayments. A reduced risk exists when the debtor’s creditworthiness is thoroughly checked in advance and the borrower's creditworthiness is assessed.
Obligations can arise both from loans or credits and from other legal relationships such as a purchase contract. It does not always have to involve only one creditor.
A debtor can also have multiple creditors. However, in enforcement, only the creditor who enforces the title is referred to as the enforcing creditor. If multiple creditors are present, insolvency proceedings are initiated against the debtor. In insolvency proceedings, the creditors form a community that represents its interests uniformly in creditors' meetings and asserts all claims against the debtor.
Termination of obligations
An obligation can end by performance of the contract. In this case it is extinguished. However, there are other possibilities that lead to the termination of the obligation.
If the creditor accepts a different performance than the one owed (acceptance in place of performance), the obligation also terminates. Acceptance in place of performance must be distinguished from performance in satisfaction (Leistung erfüllungshalber). In the latter case, the original liability remains in place and is merely deferred until the creditor obtains from the new obligations what is legally due to him. Performance in satisfaction therefore means that a debtor incurs an additional obligation alongside the original liability toward the creditor.
Furthermore, an obligation can also be extinguished by set-off. If the performances of the parties are similar in subject matter, there is the possibility of setting claims off against each other.