Construction financing by MAXDA
Construction financing usually consists of equity and a loan. With MAXDA, however, construction financing without equity is also possible.
Interest rates for a construction loan are usually significantly lower than those for consumer loans, which is why it’s worth taking a look at MAXDA construction financing if you want to buy a house or an apartment.
Especially for construction financing it makes sense to do a comparison to identify the lowest possible interest rates. MAXDA construction financing offers a cost-effective way to finance real estate!
Below we show you exactly what construction financing is, which factors are important when choosing a loan and how you as a borrower can save a lot of money with MAXDA construction financing!
The advantages of MAXDA construction financing at a glance!
Never before has the desire of Germans to own their own property and move into their own home been greater. Construction financing via loan is often used by property buyers because equity is rarely sufficient to cover the entire financing.
The advantages of MAXDA construction financing at a glance!
What is construction financing?
Construction financing is a loan taken out to finance the construction or purchase of a property including land. In most cases, construction financing is secured by a mortgage right, which today is almost always entered in the land register as a land charge on the property to be financed. If the borrower can no longer meet their loan obligations, the bank has the security of being able to satisfy its claims through a forced sale of the property. From this there are some interesting characteristics of mortgage financing for you as a borrower:
- Interest rates are at a lower level than for a conventional consumer installment loan.
- Relatively large sums can be financed even with modest means.
- Interest rates (i.e. the interest) are usually fixed for a long period.
- Individual repayment rate: The amount of repayment can be adjusted at the start within certain limits to suit your financial situation.
Construction financing without equity
Whether you dream of your own house with a garden, prefer a city apartment or want to renovate a property you already own: the MAXDA mortgage loan makes your construction financing possible, even with a negative Schufa and, if desired, as construction financing without equity!
The decision which financing to choose for the house or apartment should be carefully considered. After all, it is a long-term commitment for the property buyer. Therefore MAXDA provides lots of information on the topics of real estate and construction financing.
If you still have questions—which is perfectly normal for such a complex area as mortgage loans—do not hesitate to contact our financial experts.
How to get MAXDA construction financing!
- Minimum loan amount €25,000
- You intend to occupy the financed property yourself
- Purchase, refurbishment or conversion of a property
- You want to refinance a loan or switch a construction loan
- It is not a new build, leasehold or a listed (heritage) property
- You have been in permanent employment for at least 6 months
- Your income is not derived exclusively from self-employment
- Pensions and child benefits are taken into account when calculating income
Conditions for the MAXDA mortgage loan
From a nominal interest rate of 1.2% MAXDA offers loans from €25,000 up to €300,000, provided you use the property yourself.
A regular renovation (not a full renovation) or conversion of the property can also be financed with a loan. Refinancing of mortgage or consumer loans or the settlement of outstanding invoices is also possible.
Are there negative entries in the Schufa? Contact us, we will find a solution.
MAXDA construction financing even with a negative Schufa
For those who dream of a house and garden or an owner-occupied apartment: construction financing initially seems complex and requires gathering information and comparisons, but it is almost always feasible. You just need to choose a suitable model that reflects your individual wishes while keeping financial risks within limits — such as construction financing with a negative Schufa, as MAXDA offers.
Almost everyone experiences a temporary critical financial situation at some point; if a negative entry is recorded in the Schufa, for example because too many loans were taken out and not serviced evenly, a bank will often reject a construction financing application.
MAXDA construction financing is also possible for people who temporarily have Schufa problems or a low Schufa score. Here MAXDA offers tailor-made mortgage loans.
Construction financing: MAXDA loan with good credit history
- Up to max. 130% above the lending value
- Loan amount from €25,000 to €300,000
- Financing for owner-occupied properties
- Income from dependent employment
- Child benefits and pensions are taken into account
MAXDA construction financing with poor credit history
- Up to max. €50,000 above the lending value
- Loan amount €25,000 to €300,000
- Financing for owner-occupied properties
- Income from dependent employment
- Child benefits and pensions are taken into account
- Elimination of negative entries if justified
Financing is excluded for listed (heritage) properties, leasehold properties, new builds, insolvencies (ongoing or completed) and if your income comes exclusively from self-employment.
Mortgage financing = construction financing?
As you can see, MAXDA offers tailor-made construction financing and solutions for your individual situation. By the way, when people colloquially talk about construction financing, they generally mean mortgage financing.
When privately financing a property, equity can include savings account funds, as well as personal contributions or securities. Employers or private individuals in your circle (friends and relatives) sometimes also provide a loan in a small amount, enabling cheaper construction financing.
By the way, loans for private mortgage financing are generally secured by a mortgage on the financed property, usually in the form of a land charge.
Process of private construction financing
Do you no longer want to rent and prefer to own something of your own? Have you decided on a property, such as a terraced house, but don’t know how to initiate construction financing?
We’ll help you and prepare a non-binding offer for MAXDA construction financing!
An annuity loan is the most common route for construction financing with borrowed capital. The loan for the property (for a house, apartment or renovation) is repaid over a fixed period. With the annuity loan the repayment is directly part of the loan repayment and thus reduces the interest burden over time. The repayment rate increases continuously.
The loan in construction financing is usually not taken out for the entire period necessary to pay off the loan in full. Fixed-rate periods of 5, 10, 15 or sometimes 20 years are common here. Rule of thumb: the shorter this period, the lower the interest rate usually is.
What are the framework conditions of construction financing?
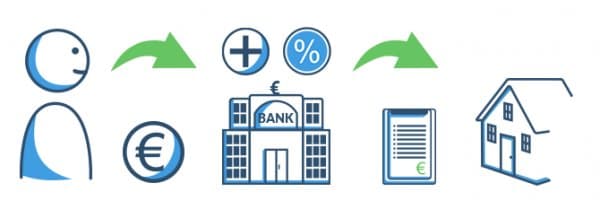
Today, mortgage financing is in many cases granted as an annuity loan. Thus you repay the loan in always identical installments. However, within each installment the ratio between interest and repayment changes with every payment. The repayment portion steadily increases while the interest portion decreases correspondingly. This is because banks only charge interest on the outstanding debt, which decreases slightly each month. The most important factors of a mortgage loan result from the structure of the financing type:
- Fixed nominal interest rate: This is the interest rate you as borrower pay for the loan. In most cases it is fixed for the duration of the fixed-rate period and therefore does not change.
- Fixed-rate period: The fixed-rate period indicates the period for which the interest rate is fixed. During this time the mortgage loan can only be terminated by you as borrower in absolute exceptional cases against payment of a prepayment penalty. After the fixed-rate period has expired, new negotiations take place, and at that time you can also refinance (switch banks). In that case you use the offer of another bank for your follow-up financing.
- Initial repayment: You can set the initial repayment yourself. It describes the percentage share of the loan amount that you want to repay in the first year. Later the repayment increases due to shifts within the annuities (regular equal installments).
- Equity: Your own funds also play a very important role in construction financing. They determine the share of the purchase price that you have to finance. The more equity you bring in, the lower the loan amount. This affects both the absolute costs of the financing and the interest rate, because lower loan-to-value ratios bring better interest conditions.
| Note: Even if a construction loan cannot normally be terminated early during the fixed-rate period, the legislator has left a gap for you as a borrower. According to §489 para.1 no.2 BGB, a construction financing loan can be terminated at any time without giving reasons after a fixed-rate period of 10 years with six months’ notice. A prepayment penalty is not due in this case. |
Based on the framework conditions mentioned above, a mortgage financing can already be outlined very well. This results in the most important figures. The following example is intended to illustrate this more precisely:
| Item | Amount |
| Loan amount | €200,000 |
| Fixed nominal rate | 2.0% p.a. |
| Fixed-rate period | 15 years |
| Initial repayment | 2.0% |
Table 1: Example terms of construction financing
These example terms show exactly the regular costs you must plan for and which outstanding balance remains after the end of the fixed-rate period:
| Item | Amount |
| Fixed nominal rate | 2.0% p.a. |
| Fixed-rate period | 15 years |
| Initial repayment | 2.0% |
| Monthly loan payment | €666.67 |
| Interest costs over 15 yrs | €50,095.65 |
| Outstanding balance after 15 years | €130,095.65 |
Table 2: Example calculation for construction financing
As you can see, in this example you would have to transfer €666.67 per month to the bank. After the 15-year fixed-rate period you would still have an outstanding balance of €130,095.65. For this amount you would need to arrange follow-up financing, either with the previous bank (prolongation) or with a new bank (refinancing). The interest rate is renegotiated and is based on the then current interest rate level.
Which aspects are still important for a mortgage loan?
In addition to the basic framework conditions mentioned above, there are other factors you should consider in a mortgage financing. These include:
- Sondertilgungen (Additional repayments)
Sondertilgungen provide the option of making additional repayments in addition to the agreed repayment. While 10–20 years ago only very few banks offered free additional repayments for mortgage loans, additional repayments of 5–10% of the outstanding balance per year are now quite common. If you have the necessary financial means, additional repayments are a very effective way to significantly reduce the costs of construction financing. To illustrate this, we add an annual additional repayment of €2,500 to the above loan during the 15-year fixed-rate period:
| Item | Amount |
| Fixed nominal rate | 2.0% p.a. |
| Fixed-rate period | 15 years |
| Initial repayment | 2.0% |
| Additional repayment | €2,500 per year |
| Monthly loan payment | €666.67 |
| Interest costs over 15 yrs | €44,304.48 |
| Outstanding balance after 15 years | €86,804.48 |
Table 3: Example calculation of the effect of additional repayments on construction financing
The savings are obvious: with an annual additional repayment of €2,500 you can save more than €6,500 in interest costs alone and the outstanding balance after 15 years is only €86,804.48. The saved interest costs due to the lower outstanding balance during the term were additionally invested in loan repayment.
- Additional costs and reserves
When calculating construction financing, it is important to include the incidental purchase costs of a property. In addition to the purchase price, other cost items arise:
- Notary costs and costs for registering the land charge and the new owner in the land register (together approx. 2% of the purchase price)
- Valuation costs for determining the lending value by the bank
- Property transfer tax (between 3.5% and 6.5% of the purchase price — depending on the federal state)
- Broker fees (between 3% and 6% of the purchase price plus VAT)
- For a build, development, insurance and building permit costs arise as incidental costs
For this reason you should always allow approx. 10–15% of the purchase price as additional incidental costs and include this in the financing cost calculation.
Moreover, especially when building a property, it can be sensible to plan an additional reserve of €10,000 because construction work can be delayed and follow-up financing is usually very expensive.
Funding options for construction financing
If you are interested in a home of your own, it is always sensible to examine possible funding options before finalizing mortgage financing. These provide significant financial help for future builders and appear today in various forms. In addition to subsidized loans there are also tax advantages or repayment and investment grants. But which funding suits your situation? To give you a better overview, some well-known funding programs are explained below.
Property funding through the Kreditanstalt für Wiederaufbau (KfW)
The KfW is one of the most important institutions for supporting private individuals in the area of home ownership and offers a number of funding programs. These include in particular:
- KfW Home Ownership Program (No. 124)
This funding program is specifically designed to finance the purchase of owner-occupied homes and condominiums. The special advantage here is the significantly discounted loan conditions, which usually offer considerable savings compared to market levels. The modalities are summarized in the following table:
| Item | Value |
| Type of loan | Depending on needs: annuity or bullet loan |
| Maximum possible funding | €50,000 per project |
| Fixed-rate period | Depending on preference: 5 to 10 years |
| Security | Secured by a land charge |
| Additional repayments | Possible against a prepayment penalty |
| Interest level | Approx. 0.5–1.0% below market interest rates |
| Conditions | Property must be owner-occupied |
Table 4: KfW Home Ownership Program — Modalities at a glance
Due to the €50,000 limit, the KfW Home Ownership Program is only a supplement to conventional construction financing. Nevertheless, such a subsidized loan can significantly reduce the overall costs of construction financing.
- Energy-efficient new construction (No. 153)
The KfW program "Energy-efficient new construction" places special conditions on funding via a subsidized loan. To take advantage of this as a builder you must build a property according to the KfW efficiency house standard 55, 40 or 40 Plus, or buy such a property as a first buyer. Particularly attractive is the repayment subsidy, which is oriented to the standard achieved. Modalities at a glance:
| Item | Value |
| Type of loan | Depending on needs: annuity or bullet loan |
| Maximum possible funding | €100,000 per housing unit |
| Fixed-rate period | Depending on preference: 10 to 20 years |
| Security | By agreement |
| Additional repayments | Possible at any time free of charge |
| Interest level | Approx. 0.5% below market interest rates |
| Repayment subsidy |
|
| Conditions |
|
Table 5: KfW Program Energy-efficient new construction (No. 153) — Modalities at a glance
The repayment subsidy makes this funding particularly attractive, since it significantly shortens the term of your construction loan and thus saves further interest costs.
- Energy-efficient renovation (No. 151)
This funding program is primarily available to property owners who want to renovate their properties to make them more energy-efficient. Buyers of a renovated property can also benefit from this, but only if the renovation costs for the property are separately itemized and can thus be calculated separately. Greatly reduced interest rates make this program attractive, and repayment subsidies for renovations can amount to up to 27.5% of the loan amount (up to €27,500 per housing unit).
In addition to programs for building or buying property, the KfW also offers numerous funding options for age-appropriate conversions, the use of renewable energies and measures regarding burglary protection.
Housing funding through the individual federal states
The federal states provide funding programs under their housing promotion laws. These programs are mainly targeted at the following groups:
- Families with children
- Single parents
- Persons with severe disabilities with special housing needs
The programs differ by state, but there are some aspects that are found almost everywhere:
- Focus on low-income applicants (certain income limits must not be exceeded)
- Requirement for equity (between 15% and 25% of construction costs — sometimes can be provided as own work)
- Limits on construction costs and apartment sizes (luxury properties are not funded)
Furthermore, the creation of rental housing is also supported. To use these, potential landlords must comply with certain rent caps and rental binding periods. Within these limits landlords may only offer the corresponding apartments to socially disadvantaged households.
Wohn-Riester – the homeownership pension
Are you an employee or civil servant subject to pension insurance? In this case Wohn-Riester may be of interest to you. It allows repayment of construction financing with your private pension savings. There are two scenarios to distinguish:
- You already have a Riester contract
If you have already taken out a conventional Riester pension as a savings product (pension insurance, savings plan), you can use the capital paid in there wholly or partially to repay a construction loan. For a partial withdrawal, however, two rules apply:
- You must withdraw at least €3,000
- You must leave at least €3,000 in your Riester contract
Thus a partial withdrawal is only possible from capital balances of at least €6,000. With the money you can for example make regular additional repayments while continuing to pay into the Riester contract and receive allowances.
2. You have not yet taken out a Riester pension
In this case the above option is of course also available to you. You can also use your contributions and the state allowances directly to repay a mortgage. Alternatively, you can use them to conclude a building savings combination financing (Bausparkombifinanzierung). Here you take out an advance loan that you initially do not repay, but only pay interest on. At the same time you save into a building savings contract and repay the advance loan when the building savings contract is allocated. A third variant is to first save into a building savings contract. You then use the later building savings loan as construction financing.
Advantages and disadvantages of Wohn-Riester
Wohn-Riester can be an interesting alternative in construction financing because the state allowances can provide attractive gains:
| Allowance | Amount |
| Basic allowance | €154 per year |
| Child allowance (children born before 2008) | €185 per year |
| Child allowance (children born after 2008) | €300 per year |
| One-time young professional bonus (contract concluded before the 25th birthday) | €200 |
Table 6: Overview Wohn-Riester
An additional advantage is the special expense deduction, since the savings plus the allowances can be claimed as special expenses for tax purposes. However, the allowances received must be deducted in the end. If this results in a further saving, you can benefit twice. But of course Wohn-Riester also has disadvantages:
- Wohnförderkonto (home promotion account): Riester contributions are recorded in the home promotion account and the sum is credited annually at 2%. The amount resulting from this must be paid as tax no later than when you turn 68. Savers can either repay the home promotion account at once and benefit from a 30% discount or repay the amount in equal installments until the age of 85.
- Requirements for the use of the property: If you support your construction financing with Wohn-Riester, the legislator imposes certain requirements. You must live in the subsidized property yourself. During your working life rental is possible, but in old age owner-occupation is compulsory. Those who violate this must repay the allowances received.
Construction financing – step by step
The process of construction financing is divided into several steps, during which you are particularly challenged in the initial phase. Below we explain these individual steps in more detail.
Step 1: Assess your own financial possibilities
Before you become interested in a particular property or construction project, it is important to know your own financial capacity. Only by knowing your financial situation can you make a reliable decision about whether certain properties are affordable and what loan amount is available to you at most. To do this, it is first important to know how much money you can afford monthly for repaying a mortgage. Calculating the maximum possible loan payment includes the following considerations:
- What regular income do I have?
If you want to pay for something, the money must be regularly available as income. For this reason the first step is to calculate your monthly regular income. Income includes:
- Regular salary payments (consider all persons in the household!)
- State benefits such as child benefit
- Interest and other capital income
- Rental income from already owned properties
By adding up all regular income you can calculate your total monthly income. Use net amounts here because only that money is actually available to you.
- What regular expenses do I have?
To determine the monthly amount available for loan repayments, you must offset your income against regular expenses. These include:
- Rent and utilities
- Energy (electricity, gas)
- Telecommunications (landline, mobile, internet)
- Hygiene (personal care and cleaning supplies)
- Food
- Insurance (e.g. liability, household contents or occupational disability insurance)
- Car expenses (fuel, taxes, insurance)
- Club membership expenses (e.g. gym)
- Leisure expenses (use averages and calculate generously)
- Payments for existing loans
- Regular savings contributions
- How large should the emergency reserve be?
Life is very varied and can change. This also applies to your financial situation. The birth of another child, for example, changes both income and expenses. In addition, unforeseen things can always happen that require repairs or important replacement purchases. For this reason you should plan a monthly emergency reserve of €100–150 as an additional expense. It can also be sensible to save for plans such as a holiday. For this you can, for example, plan another €50 per month.
From these three considerations you can now calculate the maximum available loan payment. The following example illustrates this with fictional numbers:
| Income | |
| Net salary person 1 | €2,200 |
| Net salary person 2 | €1,700 |
| Total | €3,900 |
| Expenses | |
| Rent and utilities | €700 |
| Energy | €70 |
| Telecommunications | €80 |
| Hygiene | €120 |
| Food | €500 |
| Insurance | €180 |
| Car expenses | €350 |
| Leisure expenses | €200 |
| Savings | €200 |
| Total | €2,400 |
| Emergency reserve | |
| Reserve | €150 |
| Holiday savings | €50 |
| Total | €200 |
| Calculation | |
| Income | €3,900 |
| Expenses | €2,350 |
| Emergency reserve | €200 |
| Available loan payment | €1,300 |
Table 7: Determining the available loan payment — an example calculation
| Important: Calculate generously for expenses and reserve amounts. It is always better to have a little more left at the end than to calculate too tightly and then face sudden problems. |
Step 2: Review your equity
If you want to conclude construction financing today, it is possible without equity. However, it is considerably easier if you bring 20–30% equity, as banks then calculate a significantly lower loan-to-value and can thus offer you better conditions. For our example we simply assume that €30,000 equity is available through savings.
\
Step 3: Realistically estimate the loan amount
As a borrower, what interests you most before construction financing is what loan amount you can expect. Only with concrete numbers can you view properties that are financially within reach. To calculate the maximum possible loan amount for mortgage financing you actually need the terms of the respective mortgage. For this reason it makes sense to play through at least two scenarios. Look at the current interest level and assume once favorable and once rather expensive conditions:
| Scenario 1 – cheap construction financing | Scenario 2 – expensive construction financing | |
| Fixed nominal rate | 1.7% | 3.0% |
| Initial repayment | 2.0% | 2.0% |
Table 8: Possible scenarios for loan amount
With a simple formula you can now roughly estimate the maximum possible loan amount:
(Possible loan payment x 12 months x 100) / (Interest rate + repayment (each in percentages))
For the two scenarios above this results in the following loan amounts:
| Scenario 1 – cheap construction financing | Scenario 2 – expensive construction financing | |
| Fixed nominal rate | 1.7% | 3.0% |
| Initial repayment | 2.0% | 2.0% |
| Loan amount | €421,621 | €312,000 |
| Equity | €30,000 | €30,000 |
| Purchase price | €451,621 | €332,000 |
Table 9: Possible scenarios for loan amount
| Note: If you increase the initial repayment, you can realize a lower loan amount. However, you can become debt-free faster and also reduce interest costs. Moreover, the possible loan amount also depends on other creditworthiness factors. |
Step 4: Search for suitable properties or construction projects
With the information gathered above you can now search for properties that fit within your price range. Planning a building project is also possible. Once you know exactly which property suits you and you have found one, it is time to look for a suitable construction loan.
Step 5: Compare offers and choose the right construction financing
Before deciding on construction financing, you should definitely compare various offers. Interest differences between providers can be considerable. For this reason we at MAXDA compare the conditions of numerous financial service providers to offer you the most attractive terms possible. The following example illustrates the saving potential a loan comparison can bring in the area of construction financing:
| Loan A | Loan B | |
| Loan amount | €200,000 | €200,000 |
| Fixed nominal rate | 1.70% p.a. | 2.30% p.a. |
| Initial repayment | 3.60% | 3% |
| Payment | €883.33 | €883.33 |
| Term | 20 years | 20 years |
| Total interest costs | €40,636.09 | €59,814.77 |
| Outstanding balance after 20 years | €28,636.89 | €47,814.77 |
| Savings | €12,956 | |
Table 10: Example calculation of the saving potential through a loan comparison
In this example the interest savings were completely invested in a higher initial repayment so that the monthly payment is the same for both financing alternatives. But after 20 years Loan A has an outstanding balance of only €28,636.89, while Loan B still has €47,814.77 to be repaid. The difference between these two amounts would have to be paid in interest for Loan B. The difference of more than €19,000 is a strong argument to compare construction financing beforehand. The example only assumes an interest difference of 0.6 percentage points, while in practice even larger differences can be found. So use our loan comparison and save a lot of money in the long run!
Step 7: Plan the follow-up financing 2–3 years before the fixed-rate period ends
After the fixed-rate period expires there is usually an outstanding balance that you must continue to finance. The so-called follow-up financing can either be carried out with your own bank or by switching the financing provider. In this area you should especially consider the following aspects:
- Obtain offers: Your bank will typically contact you before the fixed-rate period ends and send you an extension offer (prolongation). Be sure to also obtain offers from other banks. Even if you do not want to switch, it improves your negotiating position and you can point to cheaper competition.
- Forward loan: Mortgage interest rates are subject to market fluctuations, so interest levels can be higher or lower regardless of your creditworthiness or the provider’s pricing policy. If a particularly low interest rate occurs some years before your fixed-rate period expires, you can secure this rate for the future with a forward loan. This is possible up to 5 years in advance. Although forward loans incur commitment fees, it often pays off with especially low rates.
If you plan early for follow-up financing and obtain various offers, you may be able to significantly reduce the costs of your construction financing.
Frequently asked questions about construction financing
Below the most frequently asked questions about construction financing are answered clearly and comprehensively:
Can I get construction financing without equity?
In principle it is possible to obtain construction financing without equity. However, there are some particularities you should know in advance:
- Higher payments: Since you have to repay the entire purchase price, payments over comparable periods are considerably higher. This can become a heavy financial burden in the long run. For this reason it is advisable to calculate your financial possibilities conservatively.
- Higher interest rates: Construction financing without equity sets the loan-to-value to the maximum. As this is generally riskier for banks, they charge corresponding interest surcharges. The costs of such a loan can therefore be higher.
- Higher risk: If the construction financing fails, you are left with a significantly larger mountain of debt. It can even happen that debts remain after a forced sale.
Construction financing without equity (full financing) is therefore mainly interesting for young people with higher incomes who do not want to save up capital first. It can also be an option for civil servants in higher positions (high and secure income). Those who can repay quickly offset some structural disadvantages of this loan type and keep costs under control.
What are the advantages and disadvantages of construction financing without equity?
The advantages and disadvantages of construction financing without equity result from the special circumstances:
| Advantages | Disadvantages |
|
|
Table 11: Advantages and disadvantages of construction financing without equity
Are the interest rates of construction financing fixed?
Many construction financings today are offered with an interest rate fixed in the loan agreement. This has the advantage that you as borrower can plan reliably with consistent costs over a long period. In return, the bank has the security that you cannot simply terminate your loan during the fixed-rate period and switch to another provider. On request, however, many mortgage loans are still available today with a variable interest rate. Here the rates are adjusted at regular intervals according to market conditions.
Equity for construction financing – what counts?
Industry experts repeatedly recommend providing between 20% and 30% of the purchase price as equity in mortgage financing. This ensures an acceptable loan-to-value and thus attractive interest conditions. But what exactly counts as equity? The following assets can be included:
- Savings (cash or account balances)
- Stocks (if reasonably sellable)
- Plots and properties (can serve as collateral)
- Precious metals
It is also possible to provide part of the equity through personal work when building a property. With craftsmanship and appropriate know-how, various tasks can be performed as own work. These include, in addition to wallpapering and renovating, the design of the outdoor area or the construction of a carport. With serious planning, banks may recognize own work as equity up to 15% of the purchase price. This also enables people with less cash to contribute equity to construction financing.
| Attention: Own work can quickly get out of hand and overwhelm you timewise. For this reason it is important to think carefully in advance how much time you can devote to your house in addition to your employment. Later delays can be expensive. |
What determines the interest rate for financing my property?
The interest on a mortgage loan is the fee for borrowing money. Banks calculate their costs and pass the money on to you as the borrower with their own profit margin. In addition, banks also price in a possible default risk into the interest rate. The more likely the complete and regular repayment by you is, the lower the interest rates offered to you. From these basic considerations the following influencing factors on the interest rate of a construction financing emerge:
\
- The general interest level
General market developments influence the costs a bank must incur to obtain capital for construction financing. There is a close link between yields on covered bonds and mortgage interest rates, since banks refinance their mortgage loans accordingly. Regardless of the interest level, differences between providers’ conditions remain. An example illustrates this:
| Interest level | Low | High |
| Cheaper provider | 1.3% | 3.5% |
| More expensive provider | 2.3% | 6.5% |
Table 12: Example table interest level
- The pricing of the credit providers
The concrete interest rate of a mortgage depends of course also on the pricing policy of the respective bank. Financial service providers have different pricing structures and thus can offer financing to customers at different levels with profit. With the MAXDA loan comparison you are on the safe side, because we compare numerous offers to provide you with the most attractive interest conditions.
3. Your creditworthiness
Another important factor is your personal creditworthiness as a borrower. This consists of two parts:
- Financial capacity: Here the focus is on your income and asset situation. The higher your available income, the more reliably you can repay construction financing. Banks reward this with favorable interest rates.
- Payment behavior: In addition, your past payment behavior plays an important role. This is expressed, for example, by the SCHUFA report. A high SCHUFA score helps you obtain the most favorable mortgage conditions.
- The loan-to-value ratio
If you want to finance a property, the bank will first have the property valued and determine its lending value. This is the value that the property could achieve in the long term independently of market fluctuations if sold. From the lending value the loan-to-value ratio can be calculated as the quotient of the loan amount plus prior encumbrances and the lending value. A loan-to-value ratio of 60% means that 60% of the lending value is used as collateral for the house. The higher the loan-to-value ratio, the greater the default risk. This is associated with interest surcharges. Many banks set an upper limit at loan-to-value ratios of 80–90%, but there are exceptions. With MAXDA financing up to 130% of the lending value can be realized.
5. Special performance features
If you opt for special performance features for your property, banks will normally charge interest surcharges. These features include among others:
- Additional repayments (now often available)
- Longer commitment periods
How do I get KfW subsidies for my construction financing?
If you are interested in KfW funding for your mortgage financing, you can obtain it through your house bank or other banks. You first apply for construction financing and additionally complete the application for the respective funding program. The bank then assesses whether you are eligible for a funding program.
| Attention: Since many KfW subsidies are tied to certain conditions, you must also prove them later. This starts with the purpose binding of the funds provided and ends with achieving certain efficiency house standards, for which attractive repayment grants are sometimes paid. |
Which documents are required for construction financing?
For a bank to approve construction financing, the bank officer needs various documents from you:
\
- Proof of income
The information you provide about your income must be proven beyond doubt. For this it is important to present pay slips for the last 3–6 months and also send the latest income tax assessment to the bank. It is not uncommon for a profit-and-loss statement to be required, which can often be completed online. These details are backed by standardized procedures to calculate average expenses.
2. Proof of equity
You must also prove your equity to the financing bank. This can be done most easily via account statements from savings accounts or investment accounts. Loans from relatives should also be recorded in a contract so that they can be recognized as equity.
3. Proof of additional lenders
Do you want to process your construction financing via several channels in parallel? In this case you should of course also provide your bank with proof of corresponding confirmations (loans from building savings contracts, subsidized loans, construction loans from other banks), as this is important for planning.
4. Documents for the desired property
So that the bank can estimate the lending value of a property, it needs the relevant documents. These include:
- Land register excerpt
- Site plan
- Floor plan
- Living area calculation
- Photos (for existing properties)
- Purchase contract
Start planning now and soon move into your own home!
A construction financing is likely to be the largest financing project private individuals undertake in their lives. With careful planning and a good choice of provider, the dream of owning a home can come true. Start today and use the advantages of MAXDA construction financing!
Feel free to use our advisory service or submit a non-binding request.