Car financing – many routes lead to the goal
Many loan requests relate to the financing of a new car. For this purpose, banks have developed special loan types aimed at car financing. These are effectively installment loans that are repaid gradually.
Especially when you have found an inexpensive installment loan that has no hidden catches, you can safely finance a car with a loan. A prerequisite for a successful car financing is that the repayment is manageable and that you do not overextend yourself financially. However, there are other forms of car financing. To give you an overview, we will now examine this topic in more detail. We will show you the different forms of car financing and also what advantages a car loan from MAXDA can bring you.
When is car financing sensible?
On the other hand, financing a car with an installment loan (/en/installment-loan) is a double-edged sword. What happens if the car is accidentally damaged or becomes unusable through your fault and you still have to pay the installments?
That is of course more than annoying, and therefore the question arises whether one should purchase consumer goods at all with a loan?
These items can be affected, and the widespread availability of loans makes purchasing consumer goods by borrowing tempting. In addition, it should be considered that a car typically falls into a price range that you cannot easily cover from your income alone.
You should think about this before signing. However, there are numerous situations in everyday life in which a car is very important. Often, for example, you are forced for professional reasons to acquire a car quickly, making car financing unavoidable.
Other possible reasons:
- Living in a rural area (even the simplest things like shopping are not realistically doable without a car)
- Commute to work (the workplace is very poorly accessible by public transport)
- Time flexibility (with public transport you are bound to schedules, while the car follows your timetable)
- Transport capacity (in many situations we need to move things from one place to another – the car is a big help)
What should I pay attention to when financing a car?
If you decide on financing via a car loan, you should include some considerations in your loan choice. After all, it is important in the end that you do not pay too high an interest rate and that the monthly financial burden in the form of the installment is not too high. For this reason, the following points are important decision criteria for car financing:
Compare interest rates and find a cheap loan
Searching for a car loan is actually not difficult today, because almost every bank offers corresponding financing. At first glance at the offers, however, you will quickly notice that the differences in terms of conditions can be very large. For this reason, it is important to compare different car loans before making a loan decision. The savings potential such a loan comparison brings is shown in the following example. The example concerns car financing in the amount of 25,000 euros and two loan offers that differ in their interest rate:
Car Loan I | Car Loan II | |
Loan amount | 25,000 euros | 25,000 euros |
Effective annual interest rate | 3.99% p.a. | 6.99% p.a. |
Term | 4 years | 4 years |
Repayment rate (monthly) | €563.57 | €596.06 |
Interest costs (term) | €2,051.31 | €3,610.71 |
Savings | €1,559.40 | |
Table 1: Example calculation of the savings potential from a loan comparison in the area of car financing
This example clearly shows how much money you can save if you choose a cheap car loan. For this reason, it is important to always compare interest rates beforehand and ultimately choose the cheapest possible car loan.
| Tip: We at MAXDA have been working for many years with a large number of banks and lenders. If you are interested in a cheap car loan, please contact us! We will carry out a loan comparison across over 100 offers for you and thus find the car financing that relieves your wallet. |
Which interest rate serves as a comparison benchmark?
When comparing interest rates in the area of car financing, it is important that you compare the right interest rates. In addition to the nominal interest rate (contractual interest rate), there is also the effective annual interest rate. This includes, in addition to the pure interest, further incidental costs. According to §6 of the Price Indication Regulation (PangV), for example, the following points must be included in the effective annual interest rate:
- Brokerage costs
- Any account maintenance fees
In principle, banks must therefore list all incidental costs that are inseparably linked to the loan agreement. This way, with one interest rate (effective annual interest rate), you know how much money you have to spend per year for a certain car financing.
Important features of a car financing
The interest rate is clearly the most important decision criterion when choosing a loan. Nevertheless, you should also keep an eye on the other services. Depending on your personal situation, these can become very valuable. The most important features include:
- Free special repayments
Free special repayments allow you to make additional repayments on top of the agreed regular repayment. This is especially interesting because by repaying faster you can save additional interest costs. Normally, you have to pay a prepayment penalty for an early repayment because the bank loses interest. However, car financing with free special repayments allows you, without a prepayment penalty, to either repay a partial amount or even the entire outstanding balance. This option is only interesting if you actually receive additional income with which you could make the repayments.
- Free payment holiday
As important as a car can be, financial bottlenecks often occur at the worst possible moment. A car loan with a free payment holiday allows you to catch your breath financially once and skip one monthly payment. The pause is only granted once a year and only if there are otherwise no payment problems.
- Free installment adjustment
Increasing or decreasing the monthly loan installment is usually associated with fees. Today, however, there are loan providers who offer installment adjustments within a certain range free of charge. This can become interesting if your financial situation changes.
- Especially fast loan application
Sometimes it is necessary that you get the money needed for a car very quickly. For these cases, there are loan offers today that can boast a fully digital application process. Here you submit the loan application online and can also upload all important documents to the respective bank. In addition, the loan contract can ultimately be signed digitally. In the best case, you receive the payout after just 1–2 days and can finance your desired new or used car.
****What exactly is the residual value of a vehicle?
The residual value of a car is exactly the value the vehicle has at a specific point in time. If a new car is still with the manufacturer, purchase price and residual value are still at the same level. But a car loses significant value with the first drive. In the first year, a depreciation of 20–30% is quite realistic, and after three years a vehicle is often worth only about half as much as it was new. The residual value is particularly important in two situations regarding cars:
- You want to buy or sell a used car
If you want to buy a used car, its residual value is of course an important figure. It determines the costs and thus also the required loan amount for car financing. To determine the residual value, you can rely on lists such as the Schwacke list or the DAT list. These contain values for all makes and model years and are updated annually. However, you should note that these only represent the normal value development. Special factors such as past accidents or particularly good maintenance can certainly influence the residual value in individual cases.
- You have a contract for residual value leasing
If you chose leasing instead of purchasing a car, you can use residual value leasing in addition to mileage leasing. In this constellation, a so-called residual value is set at the beginning of the lease period, which the car must still have at the end of the lease term. The residual value is thus the difference between the new value and the wear and tear that you pay monthly through the lease installments. At the end of the lease term, the leasing provider checks whether the car actually has the assumed residual value. If this is not the case, you as the lessee must make up the difference.
The term residual value thus has a similar meaning in the respective situation, but ultimately refers to something slightly different.
What is a three-way financing?
Three-way financing is an alternative to the conventional car financing via a car loan. The special feature is that during the term you do not pay or finance the full purchase price, but, in addition to a down payment, only a partial amount. This is repaid in equal installments plus interest. At the end of the term, you then have the choice between three different alternatives (hence three-way financing):
- You return the car
If you decide against buying the vehicle at the end, you can also return it. However, you should make sure that the vehicle is in a condition consistent with the contract. Otherwise, the dealer may charge you additional costs.
- You pay the final installment (balloon loan)
If you ultimately want to purchase the car completely, you can pay the final installment from your assets. This option, also referred to as a balloon loan, is particularly interesting if you expect a larger payment at that time. This could be, for example, a maturing fixed-term deposit or a life insurance policy that is paid out.
- You refinance the final installment
Another possibility is to take out follow-up financing for the final installment of your three-way financing. You then repay this in equal installments.
What are the advantages and disadvantages of three-way financing?
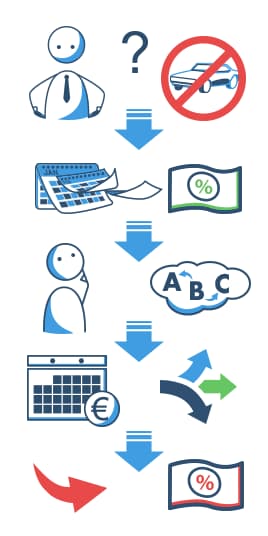
Three-way financing is particularly interesting if you do not currently have enough money to pay the high loan installments of a conventional car loan. The monthly financial burden is much lower with three-way financing. In addition, you have corresponding options at the end of the term.
Advantages at a glance:
- Low monthly burden (low installments)
- Good predictability
- Choice at the end of the term
The disadvantages lie mainly in significantly higher costs. Loans with a high final installment usually have the problem that, as a borrower, you pay interest on an amount that does not decrease during the term. Therefore, interest costs are significantly higher at the end than with a conventional car loan.
Car financing via a bank or via the dealer?
If you are thinking about buying a car, you automatically face the question of whether to finance your new car through a bank or through the dealer. Both options have their respective advantages and disadvantages:
- Cash discount with a car loan
If you use a car loan from a bank, you can benefit from an attractive cash discount. This is usually significantly higher than the discount for a dealer financing. For cash payment alone, an additional 10–20% of the purchase price as a discount is therefore possible.
- Greater choice of financing provider with a car loan
If you choose a conventional car loan, you can choose from a large number of banks and compare their conditions. With dealer financing, on the other hand, you are tied to the respective bank. Particularly attractive "0% financing" is often limited to certain promotional models.
- Favorable conditions with dealer financing
Dealer financings often offer particularly favorable conditions. Relevant discounts are usually already included in the financing offer. Sometimes you can even take advantage of 0% financing, which carries no interest. You should note, however, that these financings are limited to certain models.
Which alternative is ultimately cheaper?
This question cannot be answered definitively, because it always depends on the circumstances of the individual case. If the cash discount is higher than the interest savings of the dealer financing, financing through a bank is cheaper. Otherwise, the case is reversed. A small example calculation should illustrate this:
Car loan | Dealer financing | |
Car purchase price | €30,000 | €30,000 |
Cash discount (16%) | €4,800 | - |
Loan amount | €25,400 | €30,000 |
Effective annual interest rate | 3.99% p.a. | 0.00% p.a. |
Term | 4 years | 4 years |
Repayment rate (monthly) | €572.59 | €625.00 |
Interest costs (term) | €2,084.13 | €0 |
Total repayment | €27,484.13 | €30,000 |
Savings | €2,515.87 | |
Table 2: Comparison between a car loan and dealer financing in an example calculation
In this example calculation, the conventional car financing is the more attractive option. But if the interest rates for the car loan were somewhat higher and the discount somewhat lower, 0% financing would be the better choice. Only a clear comparison calculation will help you avoid spending too much money.
Leasing as an alternative to car financing
Leasing has established itself as another alternative in the field of car financing. With this form of financing you do not buy the car, but borrow it for a predetermined period. Here you can use two different forms:
- Mileage leasing
With mileage leasing you pay a down payment and your lease installments. A certain number of kilometers is agreed. If you have driven more kilometers than agreed by the end of the term, you must pay extra for them. Shorter mileage is now usually refunded by good leasing providers.
- Residual value leasing
Residual value leasing is based on an agreed residual value that the vehicle must still have at the end of the term. You also make a down payment and pay the agreed lease installments. If the residual value at the end of the term deviates to your disadvantage from the agreed residual value, the dealer will charge you the difference.
Leasing offers the great advantage that you can drive a new car while paying only low installments. At the end of the lease period you return the vehicle and can then get another new car at lower installments than with a car loan. Unfortunately, leasing also has some disadvantages that often make it not the best alternative for private individuals:
- No ownership: As a lessee, the car does not belong to you. At the end of the term you may have paid money but own no asset. A car owner can sell his used car after a few years at the residual value.
- Complicated: Leasing contracts are often complicated and especially the final provisions can cause problems. Additional kilometers are often charged very expensively. Even minor defects to the vehicle can cause additional costs at the end.
Leasing is certainly possible in the private sector, but is more widespread for professionally used vehicles. As a self-employed person, you can fully deduct the lease installments from taxes.
New car or used car?
Whether you should consider a new car or a used car for your purchase depends on many different factors:
- Available budget (advantage used car)
You need significantly less money for a used car and often still get a fully functional vehicle. If, when checking your financial reserves, you find that a new car is not affordable, a used car can be an interesting alternative. Both options can be financed by loan.
- Desired equipment (advantage new car)
Regarding equipment, you have much more influence with a new car. You can configure your desired vehicle in all areas so that it fully meets your needs. With a used car you have no influence on an individual vehicle and would have to wait and see whether your desired vehicle is being offered.
- Car financing (advantage new car)
Although you naturally have to take out a larger loan for a new car, you often get more favorable conditions. A new car represents an asset in itself and thus acts as a kind of security for the bank. Many banks reward this with a somewhat lower interest rate.
Tip: Do you want a nearly new vehicle at low prices? In this case, vehicles with day registrations might be interesting for you. These are often offered with discounts of up to 25% and are therefore very inexpensive. |
What happens to car financing in the event of an accident?
It is a true horror scenario: you haven't yet paid off your car and you get into an accident. What happens to the car financing in that case depends on various factors:
- Who is at fault?
If the other party caused the accident, things don't change much for you as the borrower. You receive compensation from the liability insurer of the other party and could use it to repay the car loan. Any surplus could be used as a down payment for a new vehicle. If you are at fault, however, it becomes more complicated:
- Car financing with transfer of ownership as security?
If you chose a car loan with transfer of ownership as security (Sicherungsübereignung), the vehicle registration document (Fahrzeugbrief) is held by the financing bank. In the event of a total loss, however, you need the registration document. Since the bank uses it as security, it will demand compensation. You can then secure another vehicle (possibly from a spouse). A car loan without transfer of ownership as security simply continues and you may have to pay loan installments for something you can no longer use.
The right approach to car financing
Caution is therefore required when financing a car. The question is: do you take the risk that demonstrably exists? Of course, the consideration is different if you are able to repay the installments very quickly. A cheap loan, manageable installments and sufficient liquidity are prerequisites for a secure car financing (/en/topics/loan-for-car). When financing a car, you as the borrower can choose between classic installment loans and car financings with a final installment, where the largest part of the sum is only repaid in one go at the end of the term.
Which loan is right for car financing depends on your personal financial circumstances. Contact us and we will find an attractive car financing together that fully suits your wishes and needs. This way you save time and money without having to forego good services. Take advantage of these benefits! We at MAXDA look forward to hearing from you!